Category: book riffs

  • The Innovator’s Hypothesis: Michael Schrage Tells Us How to Take the First Step

    The Innovator’s Hypothesis: Michael Schrage Tells Us How to Take the First Step

    Imagine that your organisation currently doesn’t innovate at all, but you’d like to do more (this might not be much of a stretch for some of you). What’s the best first step?

    Many organisations start with strategy. After all, we can’t innovate without a plan, right? Others will jump straight into forming an innovation team and telling them to start innovating. Some will take a light touch, and just have the CEO to tell everyone to innovate more because it’s really important.

    None of the these are the best first step. None of these create action.

    Experiments create action – start there.

    The thing is, this is harder than it sounds.  Here is a quote from Austin Kleon from his book Show Your Work:

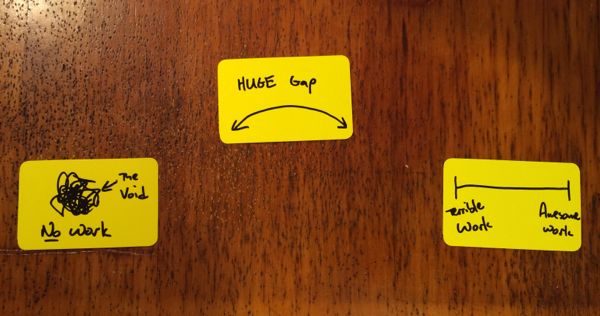
    Amateurs are not afraid to make mistakes or look ridiculous in public.  They’re in love, so they don’t hesitate to do work that others think of as silly or just plain stupid.  “The stupidest possible creative act is still a creative act,” writes Clay Shirky in his book Cognitive Surplus.  “On the spectrum of creative work, the difference between the mediocre and the good is vast.  Mediocrity is, however, still on the spectrum; you can move from mediocre to good in increments.  The real gap is between doing nothing and doing something.”  Amateurs know that contributing something is better than contributing nothing.

    I highlighted the key point – the real gap is between doing nothing and doing something.

    I’ve talked about this before. The problem with innovation strategies, and teams, and CEO exhortations is that they are mainly designed to take you along the innovation spectrum – they help with that. But they don’t get you across that gap from doing nothing and doing something.

    Experiments will.

    Though he doesn’t frame it this way, that is one of the key points that Michael Schrage makes in his new book The Innovator’s Hypothesis: How Cheap Experiments are Worth More Than Good Ideas. The book does two main jobs: it makes the case for experimenting as your core innovation skill, and it outlines the 5x5x5 technique for effectively running experiments.

    First, the gospel of innovation.  Schrage makes the case that most organisations overvalue great ideas. Here is an example of what happens as a consequence:

    But I had to ask: Why was his group so sure that “big bang” strategic approaches were best? Both on paper and Excel, my experiments offered far greater bang for the buck – and faster – than the grand plans did. Why did a simple, cheap experiment provoke such visceral negative reactions? What hot button did it push?

    His response said it all. “We think we know what he problem is,” he said. “We want a plan that’s big enough to solve it without putting our revenues at risk. You didn’t help us with that.”

    The company he was working with there? Blockbuster.

    Technology is one of the critical drivers of the growth in experimentation. Here is what Schrage said in an earlier piece with Eric Brynholfsen:

    Technology is transforming innovation at its core, allowing companies to test new ideas at speeds and prices that were unimaginable even a decade ago. They can stick features on Web sites and tell within hours how customers respond. They can see results from in-store promotions, or efforts to boost process productivity, almost as quickly.

    The result? Innovation initiatives that used to take months and megabucks to coordinate and launch can often be started in seconds for cents.

    And that makes innovation, the lifeblood of growth, more efficient and cheaper. Companies are able to get a much better idea of how their customers behave and what they want. This gives new offerings and marketing efforts a better shot at success.

    His method for doing this is pretty cool:

    The 5x5x5 design is simple and straightforward. A minimum of 5 teams of 5 people each are given no more than 5 days to come up with a portfolio of 5 “business experiments” that should take no longer than 5 weeks to run and cost no more than 5,000 euros to conduct. Each experiment should have a business case attached that explains how running that experiments give tremendous insight into a possible savings of 5 million euros or a 5-million-euro growth opportunity for the firm.

    This will work. Schrage has plenty of examples – but it also makes intuitive sense. I love this approach for a few reasons:

    • The best way to become innovative is to innovate more. Developing an innovation strategy doesn’t actually achieve this, but running a bunch of experiments sure will. Put another way –
    • Experiments will help you bridge the gap between doing nothing and doing something. By definition, running experiments require you to do something. None of the other popular first innovation steps do. They are designed to set up you to innovate. Experiments get you innovating – big difference.
    • It helps reduce perfectionism. This is a big enemy of innovation. If we have to have our ideas perfectly formed before we can execute them, then nothing will ever happen.  The emphasis on learning that is inherent in this approach is a great tool for working around this problem.
    • It shifts us from looking at expected returns to considering affordable losses. The whole point of experiments is that they are frugal – especially compared to the processes that we often use to try to help implement innovation.

    If you think you know what the problem is, like Blockbuster, you’re probably wrong, like Blockbuster this approach will be challenging to implement. But if you’re willing to try things so that you learn, then this approach is great.

    It might even make it unnecessary to develop a formal innovation strategy.  But one thing that you do need is a clear sense of purpose. That helps set the challenge that will be the organising principle for the experiments.

    Here is one last quote from the book to explain why you should experiment with experiments:

    The rhetorical and substantive importance of a provocative hypothesis to real-world innovators is difficult to overstate. The Googles, Amazons, Apples, Netflixes, and Capital Ones – not to mention world-class research universities – fluently hypothesize and culturally commit to experimentation in ways utterly alien to most commercial enterprises. These firms don’t insist on performing lots of interesting experiments because they’re rich; they’re rich because they insist on performing lots of interesting experiments.
  • There’s No Low-Hanging Fruit in Innovation

    There’s No Low-Hanging Fruit in Innovation

    There is No Low-Hanging Fruit

    I hear this idea a lot when organisations are trying to ramp up their innovation efforts:

    “We need to find some quick wins to get this going, so we’ll look for the low-hanging fruit.”

    Here’s the thing: there is no low-hanging fruit.

    If there were, we’d have picked it already. I mean, we’re not stupid, right?

    Solve the Tough Problems First

    In 10 Types of Innovation: The Discipline of Building Breakthroughs, Larry Keeley, Helen Walters, Ryan Pikkel, and Brian Quinn say:

    Solve the tough problems first.

    If we do that, the easier stuff will take care of itself later. The issue is that if we start with the easy stuff first, we may never crack the hard problems. And when that happens, the whole effort is wasted.

    This relates directly to the ideas of Peter Thiel – that going from 0 to 1 of something is the toughest task you face, and it’s worth putting in the work it takes to do this effectively. It’s doing something distinctive that actually helps you build a competitive advantage – and you get “distinctive” when you solve tough problems in a way that creates value for people.

    But About That Low-Hanging Fruit….

    Actually, I lied back in the first section. There often is low-hanging innovation fruit in larger organisations.  And, sometimes, it makes some sense to go after it.  It can help build some innovation capability.

    However, the focus on quick wins often means:

    “We’d like some of that innovation you keep talking about, just give it to us without making us change anything.”

    And that never works.

    So even if you do look for low-hanging fruit first, ultimately it has to lead you to solving tough problems.  If you’re a startup, this is what you have to work on from day one.  For organisations both big and small, solving tough problems is the only way you can build an advantage.

    And if you’re not building advantages, what’s the point of innovating in the first place?

    Photo: from flickr/kerrybuckley under a Creative Commons License.

  • Innovation Thoughts on Zero to One by Peter Thiel

    Innovation Thoughts on Zero to One by Peter Thiel

    How do we build things that move society forward? That is the core question addressed in Zero to One by Peter Thiel and Blake Masters.  I finished the book today, and here are some key quotes (in bold) and my thoughts on them.

    1. Of course, it’s easier to copy a model than to make something new. Doing what we already know how to do takes the world from 1 to n, adding more of something familiar. But every time we create something new, we go from 0 to 1. The act of creation is singular, as is the moment of creation, and the result is something fresh and strange.  Thiel’s argument is that startups that are aiming to have a big impact need to focus on building the first instance of something – going from 0 to 1.  But it’s not just startups.  Thiel also talks about how HP was successful throughout the 1990s by consistently building important new things – and that their decline started when they stopped inventing.
    2. Engineers frequently … do not understand distribution. Since they don’t know what works, and haven’t thought about it, they try some sales, BD, advertising, and viral marketing—everything but the kitchen sink…. This one is from Tren Griffin’s blog, not the book, but it’s still good (I’m borrowing Griffin’s format for this post too – he writes an excellent blog, which you should check out).  Griffin’s comment is: “Engineers have a tendency to believe that people will be lined up outside the door with crisp but non-sequentially numbered stacks of $100 bills waiting desperately to buy what they have designed.  They love what they create and think other people will too. Selling and marketing is a much harder problem than most engineers realize.” This is another version of the mousetrap problem – it’s not enough to build something new.  In fact, Thiel says that you need to answer seven questions that demonstrate that you have a clear advantage – including in distribution.  The questions are:
    3. …the seven questions that every business must answer: 1. The Engineering Question Can you create breakthrough technology instead of incremental improvements? 2. The Timing Question Is now the right time to start your particular business? 3. The Monopoly Question Are you starting with a big share of a small market? 4. The People Question Do you have the right team? 5. The Distribution Question Do you have a way to not just create but deliver your product? 6. The Durability Question Will your market position be defensible 10 and 20 years into the future? 7. The Secret Question Have you identified a unique opportunity that others don’t see? The book goes into useful detail on how to address all of these questions.  The advantage that startups have here is that don’t have path dependency locking them into the wrong answers to these questions, as larger firms sometimes do.  Flexibility is the big advantage that you have when you’re starting out.
    4. Paradoxically, then, network effects businesses must start with especially small markets. Facebook started with just Harvard students—Mark Zuckerberg’s first product was designed to get all his classmates signed up, not to attract all people of Earth. This is why successful network businesses rarely get started by MBA types: the initial markets are so small that they often don’t even appear to be business opportunities at all.  This is another problem for big companies – if you’re only looking to add new $1b product lines (or even $100m), then you won’t go into these micro-segments that you need to dominate to succeed.  This is another version of Clayton Christensen’s idea that disruptive innovations start in niches. Related to this, he has also said:
    5. Never ever hire an MBA; they will ruin your company.  That’s from an article on Slate by Nathan Furr.  It also included the diagram at the top of this post – which illustrates the issue.  There are different sets of skills that you need when you are exploring (going from zero to one) versus when you are exploiting a known idea (going from 1 to n).  Startups are usually exploring.  And it’s true, we don’t do a very good job of teaching the management skills that you need to do this in our MBA programs.  The challenge for larger firms is that you need to do both.  More on this issue soon.
    6. As a good rule of thumb, proprietary technology must be at least 10 times better than its closest substitute in some important dimension to lead to a real monopolistic advantage. Anything less than an order of magnitude better will probably be perceived as a marginal improvement and will be hard to sell, especially in an already crowded market. The clearest way to make a 10x improvement is to invent something completely new. If you build something valuable where there was nothing before, the increase in value is theoretically infinite. A drug to safely eliminate the need for sleep, or a cure for baldness, for example, would certainly support a monopoly business.  When I raise this issue in talks, people often struggle with it – how we can get a 10X performance improvement?  It’s not easy.  But there is plenty of research (not cited by Thiel) that shows that this is true.  This is why you really do need to aim high when you’re building new things.
    7. Doing something different is what’s truly good for society—and it’s also what allows a business to profit by monopolizing a new market. The best projects are likely to be overlooked, not trumpeted by a crowd; the best problems to work on are often the ones nobody else even tries to solve.  The fact that 10X improvements are hard to come by is why Thiel focuses on contrarian thinking throughout the book.  This isn’t to say that there is no value in making smaller jumps.  But most systems are dominated by the outliers – the big, discontinuous jumps.

    I don’t agree with everything that Thiel says – and some of his non-business views are pretty objectionable.  Peter Sims has a thoughtful post on his issues with Thiel’s take on monopolies, which is worth reading.  At the end of the post, Sims says:

    Sorry Peter, I don’t buy your argument, but thank you as always for provoking thought.

    I feel the same.  The book is extremely though-provoking throughout, and worth a read.  I’m still sympathetic to the little bets approach, but I also see the value in aiming high as Thiel argues.  They’re important issues to be thinking about.

  • The Future is Already Here – Find It!

    The Future is Already Here – Find It!

    William Gibson famously said:

    The future is already here, it’s just not evenly distributed.

    Here’s an example.  On one of my trips to Silicon Valley, Matt Perez invited me along to a workshop on the future of money.  As I described previously, there were a range of ideas put forward about what the future of money will look like.

    Some visions included the smallest possible increment of progress – like the bank that had invented the world’s first social credit card.  What makes it social? You can like it on Facebook.

    socialcreditcard


    Other ideas were much more ambitious, like the guys that wanted to replace the entire global financial system with currency based on tweets.

    bank with tweets

    But here’s the thing: the future of money is already here – in Africa.

    Last week on Bloomberg, Charles Graeber described a ten day trip to Kenya, where he paid for everything with a mobile phone.  Everything!

    You can’t do that here in Brisbane.  You can’t do it in Silicon Valley right now either.

    The future is here, it’s just not evenly distributed.

    sente2


    That picture is from Jan Chipchase’s great presentation called Designing Services for Financial Inclusion, which you can download here.

    The main mobile payment company in Kenya is M-Pesa – and if you look at that picture from Chipchase, you can see that it doesn’t even need a smartphone to work.

    Graeber describes how the M-Pesa system has leapfrogged the need for both landlines and banks in Kenya:

    M-pesa took off almost instantly because it made it safer for Kenyans to send money home (instead of having cash carried by a cousin, say, on a bus prone to breakdowns, traffic accidents, and theft) and because M-pesa on a SIM card allowed millions of Kenyans without a bank account to become their own personal ATMs, especially appealing to farmers between harvests. If a Kenyan didn’t have a phone, she could simply borrow one; all she needed was a SIM card to be in business.

    Much of a One Acre Fund field officer’s time involves collecting payment in person from the 80,000 client farmers in Kenya. That involves carrying around small piles of bills. The field officers have been robbed, and fraud is always a concern. Now, instead of a weekly collection, they use M-pesa to quickly deposit money. The next step, currently in large-scale trial, allows farmers to send micropayments directly to the central One Acre Fund account.

    It’s all part of a larger trend of using mobile technology and incremental payment plans to bring basic grid services to off-grid people. Companies such as Angaza Design, Off Grid Electric, Mobisol, and M-Kopa Kenya are doing this with digital microfinanced solar. Tone Kwa Tone Pata Pump (Swahili for “drop by drop gets the pump”) does something similar with farm irrigation systems; Sustainable Water & Sanitation in Africa installs M-pesa payable clean water stations.

    Here is one of the shots from Graeber’s photo essay that accompanies the piece:

    pay with M-Pesa

    This story illustrates some important innovation points.

    First off, we simply must get better at scanning and connecting ideas.  It’s not enough just to look at what our direct competitors are doing – in fact, it might be counterproductive.  Instead, we need to look into areas that face similar problems.  For example, the NHS and then other health services started to learn how to work more effectively and more safely by adopting some of the methods used by Formula 1 pit crews.

    This is one of the key components of the innovator’s DNA identified by Jeff Dyer, Hal Gregorson and Clayton Christensen.  They say:

    Innovative breakthroughs often happen at the intersection of diverse disciplines and fields. Author Frans Johanssen described this phenomenon as “the Medici effect,” referring to the creative explosion in Florence when the Medici family brought together creators from a wide range of disciplines—sculptors, scientist, poets, philosophers, painters, and architects. As these individuals connected, they created new ideas at the intersection of their respective fields, thereby spawning the Renaissance, one of the most innovative eras in history. Put simply, innovative thinkers connect fields, problems, or ideas that others find unrelated.

    As Nilofer Merchant says, the social era is about connecting things, people and ideas.  So you need to travel, meet people, and read.  By doing these things purposefully, we can improve our scanning and connecting skills.  Even if we’re introverts, we can look for experiences and ideas outside of our comfort zones.  Especially if we’re introverts…

    Finally, we need to check our assumptions. Would you have guessed that Kenya is ahead of Silicon Valley in mobile payments?  I wouldn’t have.  And yet, it is.  It’s important to break down our assumptions about how the world works (more on this later this week).  I specifically recommend paying attention to business stories coming out of China, India and Africa.  There is amazing stuff going on in all three places.

    One important point, however, is that mobile payments in Silicon Valley won’t work in exactly the same way that they do in Kenya.  We always need to adapt an idea to our local context – that’s what makes it innovation!

    But if we’re not scanning widely for ideas in the first place, we won’t even have a chance to do that.

    If the future is already here, our job is to go out and find it.  Then bring it back home and make it work there.

  • Talent is Everything, and Talent Can Be Developed

    Talent is Everything, and Talent Can Be Developed

    What are Mindsets?

    How would you answer this question? “Is a person’s intelligence fixed and unchangeable?” It turns out that the way you answer this and related questions influences how successful you will be.  This the idea that Carol Dweck outlines in her terrific book Mindset.  In a very good review of the book, Alex Vermeer provides this summary:

    Your mindset is the view you have of your qualities and characteristics – where they come from and whether they can change.

    These following two mindsets represent the extreme ends on either side of a spectrum.

    fixed mindset comes from the belief that your qualities are carved in stone – who you are is who you are, period. Characteristics such as intelligence, personality, and creativity are fixed traits, rather than something that can be developed. growth mindset comes from the belief that your basic qualities are things you can cultivate through effort. Yes, people differ greatly – in aptitude, talents, interests, or temperaments – but everyone can change and grow through application and experience.

    It’s very possible to be somewhere in the middle, and to lean a certain way in one area of life, and a different way in other areas. Dweck writes about them as a simple either-or throughout the book for the sake of simplicity. Your mindset likely varies from area to area. Your views may be different for artistic talent, intelligence, personality, or creativity.

    And this graphic by Nigel Holmes summarises the kinds of outcomes that result from the different mindsets:

    Carol Dweck Mindset

    Mindset and Innovation

    Dweck’s work has some important implications for innovation:

    • A fixed mindset is an important source of risk aversion. Risk aversion is one of the biggest innovation obstacles that we face.  You can see how a fixed mindset leads to avoiding taking a chance on new ideas.  If we work on building our growth mindsets, we can start to work our way around this problem.  Which leads to:
    • We can change our mindset. Dweck and her team have done a huge amount of carefully constructed research on this topic, and they have consistently shown that you can change your mindset.  Here is a quote from Maria Popova’s excellent post on Mindset:

      Dweck and her team found that people with the fixed mindset see risk and effort as potential giveaways of their inadequacies, revealing that they come up short in some way. But the relationship between mindset and effort is a two-way street: “It’s not just that some people happen to recognize the value of challenging themselves and the importance of effort. Our research has shown that this comes directly from the growth mindset. When we teach people the growth mindset, with its focus on development, these ideas about challenge and effort follow. . . . As you begin to understand the fixed and growth mindsets, you will see exactly how one thing leads to another—how a belief that your qualities are carved in stone leads to a host of thoughts and actions, and how a belief that your qualities can be cultivated leads to a host of different thoughts and actions, taking you down an entirely different road.”

      And, most importantly, this means that:

    • We can grow our talent. The outcome from all of this is the idea that talent is something that can be developed.  This means that it is not the case that you are either creative and innovative or you are not.  You can build these skills.

    We Develop Talent by Building Skills

    Here is more from Popova:

    Its hallmark is the conviction that human qualities like intelligence and creativity, and even relational capacities like love and friendship, can be cultivated through effort and deliberate practice. Not only are people with this mindset not discouraged by failure, but they don’t actually see themselves as failing in those situations — they see themselves as learning.

    This is a powerful idea.  When I was younger, I had a very strong fixed mindset – and it made me terrified of failing. Fortunately, the more I’ve failed, the more I’ve developed a growth mindset.  It’s taken a lot of work and effort, but I’m much better equipped to build skills now than I was when I was younger. This reflects the differences in the attitudes towards effort in the two mindsets.  With a fixed mindset, having to work hard at something is a sign of deficiency.  But with a growth mindset, hard work is the only way you grow.  I thought of this over the weekend when I read this quote in Turning Point by the great Hayao Miyazaki:

    I had thought that my passion could bridge the gap between what I wanted to express and my ability to express it.  But I saw that I couldn’t get by without acquiring the necessary skills.  I learned through bitter experience that without those skills I wouldn’t be able to express my ideas. This was when I changed.  No matter what I was working on, I would give it my all; no matter how boring the job, I would discover something new and move forward, even if just a little.  Unless one does this, one cannot make use of one’s abilities when a really important job comes along.

    Here is a great quote from Ira Glass of NPR that makes the same point:

    Hayao Miyazaki and Ira Glass both do genius-level creative work, and yet, they attribute their success to hard work. That reflects a growth mindset.

    Innovation is talent-based.  You need skilled people to innovate well.  The great news from Carol Dweck’s work is that if we have the right mindset, we can build the talent that we need.

    Of course, there are no shortcuts.  To innovate, we must practice, learn and improve.  That’s how we develop our talent.

    Enhanced by Zemanta
  • Finding the Right Innovation Balance

    Finding the Right Innovation Balance

    3M is one of the most innovative companies in the world.  Each year, their target is to have more than 30% of their revenue come from products that are less than four years old.  To do this, they must constantly come up with new stuff.

    To find this new stuff, they spend about 6.6% of their annual revenue on Research & Development.  The average large US corporation spends less than 2% of revenues on R&D, so 6.6% is a whole lot.

    But think about this for a second – what is 3m spending the other %93.4 of their money on?

    The rest of the money goes to executing ideas that they’ve already had.

    One of the challenges of innovation management is finding the right balance between the old and the new.

    innovation balance


    Finding the balance between the old (the 93.4%) and the new (the 6.6%) is tricky.  You need the core business to work smoothly and efficiently in order to realise the value of your great new ideas. But this requires different skills and metrics than we need to use to come up with those great new ideas in the first place.

    Bob Sutton looks at these issues in his excellent book Weird Ideas That Work: How to Build a Creative Company.  He says:

    There is a lot of hype in the business press about the dangers of clinging to the past, and much of it is justified.  But all the excitement about building better products and companies can make us forget that most new ideas are bad and most old ideas are good. After all, that is what Darwin predicts.  The death rate of new products and companies is dramatically higher than old ones.  Dozens of new breakfast cereals fail every year, while Cheerios and Wheaties persist.

    My aim is not to convince you to discard every routine your company uses and to devote all efforts to inventing new ways of thinking and acting.  On the contrary, doing routine work with proven methods is the right thing to do most of the time.

    Does this mean that you should stop trying to innovate? Not at all.  The problem is that the world does change, new technologies are developed, competitors come up with superior products and services, and consumer preferences change.  These are the times and place when innovation is crucial. … Many companies have made a lot of money by creating new and better future. So, although it usually entails a high failure rate and a lot of resources, every company – or at least part of it – needs to keep trying to discard old ways and replace them with new and better ways.

    This is a challenge.  If we devote ourselves only to the new, then we will fail to take advantage of the great ideas that we generate.  But if we only concentrate on optimising for the present, then we’ll get killed by the future.  And the pace of that problem has increased significantly since Sutton wrote the book in 2002.

    Here is how Nilofer Merchant puts it in an excellent post on what she learned from working with Steve Jobs:

    … our job as innovative business leaders is to manage the present while inventing the future. We must recognize that we are always a product of what we’ve done and who we aspire to be. It is not enough to lead our current businesses; we must also lead our future businesses. … To grow new markets means making yourself uncomfortable.

    The part about feeling uncomfortable is also what Sutton is getting at – that is why the ideas in his book seem weird.  He recommends 11.5 ideas that you need to execute in at least part of your business in order to create the future:

    His ideas are:

    Here is the list (note I say 11.5, but there are really 12)

    1. Hire slow learners (of the organizational code).

    1 ½. Hire people who make you feel uncomfortable, even those you dislike.

    2. Hire people you (probably) don’t need.

    3. Use job interviews to get new ideas, not to screen candidates.

    4. Encourage people to ignore and defy superiors and peers.

    5. Find some happy people, and get them to fight.

    6. Reward success and failure, punish inaction.

    7. Decide to do something that will probably fail, then convince yourself and everyone else that success is certain.

    8. Think of some ridiculous or impractical things to do, and then plan to do them.

    9. Avoid, distract, and bore customers, critics, and anyone who just wants to talk about money.

    10. Don’t try to learn anything from people who seem to have solve the problem you face.

    11. Forget the past, especially your company’s successes.

    Finally, as a summary, if you look at these, a reasonable conclusion is that, although creative places can be a lot of fun at times and being happy is linked to creativity (sort of, I’ll explain in a later post), note also that Creative companies and teams are inefficient (and often annoying) places to work.

    Sutton wrote an excellent piece for HBR that summarises the ideas in the book – which includes this graphic:

    weird ideas that work


    This is another tension in managing innovation – finding the right balance between managing the present and creating the future.  And it again shows that to innovate, we must first understand the past.

    This is hard.  If you look at Sutton’s ideas, you can see that implementing them will create tensions within an organisation.  It’s much easier to focus only optimising the present, or on building something completely new.  But those two extremes lead to failure.

    As Paul Hobcraft correctly pointed out to me once in an email – “if innovation were easy, everyone would be doing it.”

    Yep.  One of the challenges is finding the right innovation balance.  3M has done it, and so have others.  If we can too, then our odds of success go up.

    Enhanced by Zemanta
  • How to Know When Your Great Idea is Ready for the World

    How to Know When Your Great Idea is Ready for the World

    The Technology Readiness Level

    Timing is important in innovation.  When we develop new ideas, we need to know when they are ready for the world. There are a couple of tools that can help us with this.

    The first is the Technology Readiness Level (TRL) – a tool developed by NASA to evaluate technologies that they could use in their various programs.  NASA developed this tool for a couple of reasons.  One was that as the agency grew in size, their network of suppliers and collaborators became enormous.  The sheer number of new technologies that were being worked on was also enormous – and it was challenging to know when these ideas were ready to be integrated into NASA’s ongoing programs.

    The second issue was that they were being approached a lot by people that had a great idea for the space program, but nothing more than the idea itself.  NASA needed a way to show them that the ideas needed a lot more work before tehy ready to go.

    So they developed the TRL.  It looks like this:

    nasa-trl


    The TRL is used to address those two issues: to evaluate when a technology is ready to for use in flight, and to guide inventors and researchers in how prove to that their idea is useable.

    Recently, I’ve run across several organisations that are using their own versions of the TRL to evaluate their research efforts.  One of them applies this to their own internal R&D group.  When new ideas arise in the business, the R&D team works on developing them, up until they reach about TRL6.  It is at this point that they try to integrate the new ideas into the core business.

    Another public research organisation that I work with does a similar thing.  The only difference is that when they reach TRL6, they start looking for a commercial partner to help them bring the idea into the market.

    The TRL is a great tool to help you develop your new technologies and eventually get them out into the world.

    But what are technologies, exactly?

    In his book The Nature of Technology, Brian Arthur has a pretty interesting definition of technology.  He outlines this in a great interview with American Scientist:

    I discovered there was a great confusion about what “technology” meant. I wound up realizing that three different definitions were simultaneously needed. One is that individual technologies are just means to purposes, things like MRI machines or oil refining. Then there are bodies of technology, such as nanotechnology, biotechnology and electronics. And then there’s technology as a whole, where we say a culture possesses a certain collective we can call its technology. I began to realize that each one of those moves forward in time in a different way. The means to purposes are like individual species, the bodies of technology are like local ecosystems, and the whole collective is like the biosphere.

    I think a lot of other researchers have gotten into trouble because they didn’t stop to make those distinctions. There’s a big difference between radio engineering and a radio receiver. Both are “technologies,” but they are not the same types of thing at all.

    This is actually pretty interesting.  We tend to think of “technology” as stuff – like iPhones, MRI machines, and cars.  But Arthur talks about technology as also being a body of knowledge.  This broadens the definition considerably.  If a technology is knowledge about how to achieve useful ends, then management is a technology.  A business model would be a technology – basically, useful ideas are technologies.

    This means that the idea of the TRL can be used more broadly too.

    The Investment Readiness Level

    Steve Blank has done precisely that in developing a new tool that he calls the Investment Readiness Level (IRL).  The IRL looks like this:

    investment readiness level

    He initially started to use it to evaluate startups going through the Lean LaunchPad program.  Over time, he discovered that the IRL could be modified to fit different industry business models.  Here are the advantages to this that he outlines:

    • The Investment Readiness Level provides a “how are we doing” set of metrics
    • It also creates a common language and metrics that investors, corporate innovation groups and entrepreneurs can share
    • It’s flexible enough to be modified for industry-specific business models
    • It’s part of a much larger suite of tools for those who manage corporate innovation, accelerators and incubators

    The IRL is interesting for a couple of reasons.  One is that it is based on the idea that new technologies usually need new business to succeed.  The Lean LaunchPad program is based on a combination of the Business Model Canvas, Blank’s Customer Development process, and Agile Engineering.  The latter means that new product development is part of using the IRL process – IRL4 and IRL7 are both about the product.

    Combine the Two Scales for Better Odds of Success

    I think that we can use these two scales together.  For many firms that are using the TRL, their interaction with the potential users of their technology comes too late.  By the time they get to TRL6, the features of the technology are pretty well locked in.

    This increases risk.  If you are are doing basic research, you will still probably start on the TRL.  But if you’re making genuinely new things, then you need to integrate the IRL early in the process.

    The TRL helps you figure out if your idea will solve a technical problem.  But the IRL helps you figure out if your technology addresses a real need.  To succeed, you have to do both.

    If you only use the TRL, the danger is that you will create a great gadget (or process, or set of ideas) that don’t address a real need.  But if you only focus on the IRL, the danger is that you will identify a real need, but you can’t build the technology you need to meet it.

    Great new technologies (in the broadest sense of the term) need great new business models to succeed.  If you use these two tools, they will help you figure out when your great idea is ready for the world, and they will also help you make sure that the world is ready for your great new idea.

  • Can Asking Better Questions Make Us Better Innovators?

    Can Asking Better Questions Make Us Better Innovators?

    We often think of innovation as problem-solving.  One mistake in this approach is to place all of your focus on the solving part, and not enough on the problem.

    Finding better problems is actually a key innovation skill.  And you find better problems by asking better questions.

    Warren Berger looks at how innovators, entrepreneurs and other creative business leaders use questions to be more effective in his excellent new book A More Beautiful Question.

    One argument that he makes is that as the world becomes more complex, the value of answers goes down, while the value of questions goes up.  Why? Because an answer is usually very context specific, but a good question will still be valid across changing contexts.

    Question Answer Value


    In an interview at 800CEORead, he talks about the value of questions in innovation:

    Q: The book is also filled with stories of business breakthroughs that began with a question. What do you consider to be some of the more interesting examples?

    WB: The cell phone started with a question. So did The International Red Cross and the Olympics, as well as the Internet. Questioning gave us car windshield wipers and instant cameras—the latter can be traced to the question, “Why do we have to wait for the picture?,” asked by the 3-year-old daughter of inventor Edwin Land, who would later start Polaroid. Companies such as Netflix, Pandora, Dropbox, Square, Pixar, and many others can be traced back to a “founding question”—though my favorite, just because it’s so odd, involved a college football coach who asked, “Why aren’t the players urinating more?” That question led to the realization that the sweating players weren’t replenishing fluids well enough, which in turn led to the creation of Gatorade and a $20 billion sports drink industry. So while it may have sounded like a weird question, it turned out to be a beautiful one.

    This is a theme that Stefan Bucher also picks up in his book 344 Questions.  His goal in this book is to ask questions that will help creative people have the impact that they’re aiming for on the world.

    Maria Popova gives a great summary of the book, which is both beautifully designed and very useful.  Here is one of the pages from the book:

    How Are You Educating Yourself?

    Each page is framed around one core question – like How Are You Educating Yourself?  That’s a pretty good question for anyone reading this, since you’re presumably working on that right now…

    Leigh Buchanan looks at the issue of asking questions as well in a post on questions that will make your business better.  Some of my favourites from this list include:

    • How can we become the company that would put us out of business? –Danny Meyer, CEO of Union Square Hospitality Group 
    • What counts that we are not counting? –Chip Conley, founder of Joie de Vivre Hospitality and head of global hospitality for Airbnb  – Conley explains, “In any business, we measure cash flow, profitability, and a few other key metrics. But what are the tangible and intangible assets that we have no means of measuring, but that truly differentiate our business? These may be things like the company’s reputation, employee engagement, and the brand’s emotional resonance with people inside and outside the business.”
    • Are we changing as fast as the world around us? –Gary Hamel, author and management consultant
    • Did my employees make progress today? –Teresa Amabile, author and Harvard Business School professor – Amabile explains, “Forward momentum in employees’ work has the greatest positive impact on their motivation.”
    • What was the last experiment we ran? –Scott Berkun, author
    • What stupid rule would we most like to kill? –Lisa Bodell, CEO, FutureThink

    Overall, it is absolutely true that asking better questions will make us more innovative, and more effective.

    Here are some more to think about:

    • Who do you want your customer to become?  This comes from Michael Schrage’s excellent eBook – I’ve discussed it previously here.
    • What would I do differently if everyone reporting to me was a volunteer? Because in reality, they are…
    • If we were starting our business today, would we do this? Existing businesses often get locked into ineffective business models because they keep doing the things that worked when they started.  Disruption comes when one of their competitors answers this question “No!” and starts doing things differently.
    • What real needs do we meet for people?

    That last one is big.  The Center for Nonviolent Communication has put together a list of universal human needs.  If you want to build an organisation that will last, you better be addressing one of these:

    Human Needs

    Better questions lead to better answers, better innovation, and a better world. If you want to get better at it, Berger has put together a list of tips that will help.

    What questions should you be asking?

    Enhanced by Zemanta
  • To Create the Future, We Must Understand the Past

    To Create the Future, We Must Understand the Past

    One common mistake that innovators make is to focus only on the future, without regard to the present or the past.  Innovation is about making ideas real to create value for people.  No matter how revolutionary your idea is, it has to work in the real world to create value, and both of those depend on understanding the present and the past.

    Here are two quotes I’ve run across recently that illustrate this point.  The first is from Kim Wilkins in the Afterward of her outstanding book The Year of Ancient Ghosts (page 254):

    There is a tendency to see the Middle Ages as a long way off; at the far end of a spyglass.  We aren’t medieval; we’ve become modern, rational. We’ve superceded what we were in that “dark age”. But just like a spyglass, the medieval folds up inside the modern.  It inhabits us even as we try to disavow its proximity, its persistence, its always-there-ness.

    It’s a great book, and you should read it. I love that metaphor of the spyglass. And it’s true – the past is always present in our new ideas.

    The second quote comes from John Keane in his excellent book The Life and Death of Democracy (page 876):

    The working formula I use is straightforward: people inevitably misunderstand the present when they live in ignorance of the past. In every line, this book tries to impress on readers that the future of democracy depends upon the past, which is always at work in the present; and it reminds them of what we would collectively lose if the world foolishly allowed democracy to slip through its hands, to wither away, or to be killed off by its rising numbers of opponents.

    The larger point that Keane is making is that there is nothing inevitable about the spread of democracy.  It is an institution created by people, and like all such institutions, we must work to maintain it and help it grow.

    ideas don't fight

    We often think of new ideas battling older ones.  And yes, as new ideas spread, some older ideas lose strength.  But overall, I think that it’s more productive to think about ideas building up on each other, like this:

    ideas building

    When we look at the history of innovation, it becomes clear that we can’t create valuable new ideas without building on old ones.  Think about the example of computers – the device that you’re reading this on is part of a line of ideas that actually goes back thousands of years.

    To innovate, we need to be able to imagine a better world.  But at the same time, we have to be aware of what has come before.

    To create the future, we must understand the past.

    Enhanced by Zemanta
  • Things Don’t Always Go According to Plan

    Things Don’t Always Go According to Plan

    Things Don’t Always Go According to Plan

    Here’s one of my recent mistakes:

    New Cat Bed

    We bought the fish because we thought it would be a funny cat bed.

    But, of course, the cats prefer the box it came in.

    This is not unusual.  Here is James Burke in Connections:

    Things almost never turn out as expected. When the telephone was invented, people thought it would only be used for broadcasting. Radio was intended for use exclusively onboard ships. A few decades ago, the head of IBM said America would never need more than four or five computers. Change almost always comes as a surprise because things don’t happen in straight lines. Connections are made by accident. Second-guessing the result of an occurrence is difficult, because when people or things or ideas come together in new ways, the rules of arithmetic are changed so that one plus one suddenly makes three. This is the fundamental mechanism of innovation, and when it happens the result is always more than the sum of the parts. A silk loom and the 1890 U.S. census gave birth to the computer. Gaslight and the American War of Independence were responsible for raincoats. Glassmaking and English clay made possible transatlantic navigation.

    Adjusting on the Fly

    So what?  Well, here are some ideas:

    1. Use more empathy.  The cats love boxes.  Our floor is strewn with amazon boxes, and they love them.  They are a lot pickier about things that resemble caves.  We knew this, but we didn’t think like a cat when we ordered that cat bed.
    2. The purpose of our idea is discovered in use. The point of Burke’s book is that great ideas accumulate over time – and the use is not obvious in advance.  We only figure out what things are good for when we start using them, and combining them with other ideas.  That’s why it’s almost impossible to say who invented the computer – lots of people did, and the ideas that contributed to computers accumulated over thousands of years.
    3. We don’t know in advance what the great ideas are.  Check out this idea from John Cassidy on tech bubbles:

      That’s not to dismiss the great success of some of the companies founded during the tech bubble, such as Amazon and eBay. Similarly, some of the investments in the dot-com era that seemed to be wasted, such as the laying of large amounts of fibre-optic cable, turned out to be productive. Is there a way to encourage the investment and innovation we want without enduring all the consequences of a bubble?

      The problem is this: we don’t know in advance which ones are the innovations that we want.

    We get this a lot when we talk about innovation – people say, “well, just invest in the good ideas, not the speculative ones.”  That would be great, but we don’t know in advance what the good ones are.  It was in no way obvious that amazon would be able to beat out Barnes & Noble and Borders for online book sales – in fact, most people expected Jeff Bezos to fail.

    The amazon story is often told as though everyone knew that it would work in advance. But here’s Bezos in this year’s letter to shareholders:

    Failure comes part and parcel with invention. It’s not optional. We understand that and believe in failing early and iterating until we get it right. When this process works, it means our failures are relatively small in size (most experiments can start small), and when we hit on something that is really working for customers, we double-down on it with hopes to turn it into an even bigger success. However, it’s not always as clean as that. Inventing is messy, and over time, it’s certain that we’ll fail at some big bets too.

    I’m not saying “don’t plan.”  What I’m saying is “don’t expect things to go to plan.”  There’s a difference.  Planning helps you figure out  what you will do in different circumstances.  But when you’re trying something new, you have to be ready for the plan to be wrong.

    That’s why we need to build learning loops into our plans. Eventually, if we keep muddling along, we might even get things right.

    Schumpeter in the Cat Bed

    Enhanced by Zemanta
  • The Secret is That There is No Secret

    The Secret is That There is No Secret

    The Worst Buzzword in Business

    My least favourite business buzzword right now is “secret sauce.”

    Why? Because there really aren’t any secrets.

    Case 1: The Cloakroom

    I was reminded of this last week when I was talking with my friend Louis Ialenti at The Cloakroom.  As we discussed how their business is going, he said:

    The thing I like about our business model is that we’re getting very good at doing things that no one else is willing to do.

    During a period of time that has been very flat for retail, they’ve been doing exceptionally well for quite a while now.  And their secret isn’t secret – it’s mostly that they do the hard work that others are unwilling to do.

    Case 2: Saddleback Leather

    When I wanted to celebrate my promotion a couple of years ago, after a fair bit of research I settled on getting myself  a briefcase from Saddleback Leather.  Why?  Because their point of difference is also based on doing what others won’t.

    Check out this video from the founder, Dave Munson – explaining how to make a proper bootleg version of their briefcases (h/t DK):

    He just gave away all of their secrets!  Why would he do that?

    Munson is willing to give away the secrets because he knows that no one else is willing to do the work.

    Their website also includes links to others making similar bags.  Why? Because:

    Do you think that our competitors would actually put a link to our website on theirs?  I’m so confident that you’ll find our classic look and over-engineered durability so hard to resist that I want you to shop around.  Go ahead… the more you shop, the better we look.

    Case 3: Hugh MacLeod

    Here is Hugh MacLeod, from his great first book Ignore Everybody:

    I get asked a lot, “Your business card format is very simple. Aren’t you worried about somebody ripping it off?”

    Standard Answer: Only if they can draw more of them than me, better than me. What gives the work its edge is the simple fact that I’ve spent years drawing them. I’ve drawn thousands. Tens of thousands of man hours.

    So if somebody wants to rip my idea off, go ahead. If somebody wants to overtake me in the business card doodle wars, go ahead. You’ve got many long years in front of you. And unlike me, you won’t be doing it for the joy of it. You’ll be doing it for some self-loathing, ill-informed, lame-ass mercenary reason. So the years will be even longer and far, far more painful. Lucky you.

    If somebody in your industry is more successful than you, it’s probably because he works harder at it than you do. Sure, maybe he’s more inherently talented, more adept at networking etc, but I don’t consider that an excuse. Over time, that advantage counts for less and less. Which is why the world is full of highly talented, network-savvy, failed mediocrities.

    Low hanging fruit

    Case 4: Ben Horowitz

    And finally, here’s Ben Horowitz from his new book The Hard Thing About Hard Things:

    Whenever I meet a successful CEO, I ask them how they did it. Mediocre CEOs point to their brilliant strategic moves or their intuitive business sense or a variety of other self-congratulatory explanations. The great CEOs tend to be remarkably consistent in their answers. They all say, “I didn’t quit.

    The Secret is That There Are No Secrets

    The Cloakroom and Saddleback Leather are selling quality.  But the same is true if your point of difference is being the lowest cost option – you still have to pursue that end fanatically, doing more than anyone else is willing to do to cut costs.

    The secret to being different is that you have to do the work that others are unwilling to do.

    When it comes to innovation, there aren’t many secrets here either.  It’s a bit like losing weight.  If you want to lose weight, you need to do some combination of taking in fewer calories while burning more.  In other words, eat less and exercise more.

    If someone tries to sell you a diet that involves anything other than those two things, it’s a sham.

    It’s the same with innovation.  If you want to innovate, you have to try more stuff.  This sounds simple (just like “eat less” sounds simple), but it’s not easy.

    You have to do the work.  In the case of innovation, the work involves engaging the people you work with, experimenting, and figuring out how to scale what works, while learning from what doesn’t.

    That’s The Innovation Loop:

    img_0144


    If you actually think about how to do this within your organisation, you’ll realise that it leads to profound changes.  That is why people look for a shortcut.

    Or a secret.

    I’ll give you the secret: there are no secrets.

    You just have to do the work.

    (the cartoon is from Hugh MacLeod’s Daily Newsletter – subscribing to it is worthwhile)

  • We’re Not Risk-Averse, We’re Variance-Averse

    We’re Not Risk-Averse, We’re Variance-Averse

    Risk Averse or Variance Averse?

    Often, people tell me that they can’t innovate, because they are in risk-averse organisations.

    I don’t think this is true.

    First off, think about insurance companies.  They buy risk – they are actually risk-loving firms.  But many of them struggle to innovate – they are often deeply conservative.  What gives?

    They buy risk because when they have enough collective risk, it averages out to (normally) a fairly predictable set of outcomes.  The whole business is built to reduce variance.  The innovation difficulty comes not from risk aversion, but from a fear of variance.

    In my classes I often use an innovation simulation that illustrates some of the challenges of dealing with radical innovation.  Often, when students go through the complex version of this exercise the first time, they get fired.  Why? Because there is too much variance between their forecast sales and their actual results.

    In the simulation, the firm is dealing with high levels of risk – but it’s not the risk that gets you fired, it’s the variance.

    People like predictable outcomes.  Managers often need predictable outcomes.

    So when someone says that their firm is risk-averse, it almost always means that, really, they are variance-averse.

     The Plate Tectonics of Innovation

    This variance-aversion is ok, if your firm lives in a completely stable environment.  But it is a problem if we suppress variance – because that only leads to big (usually unpleasant) surprises.

    Plate tectonics make a good analogy here.  Here is a diagram of a typical subduction zone that leads to earthquakes, volcanoes, and tsunamis.

    subduction zone

    The oceanic plates slowly expand over time.  When they meet the thicker continental plates, they slide underneath them.  The oceanic plate melts, and this heat causes volcanoes.

    It is friction between the plates that causes earthquakes.  As the two plates slide past each other, they catch and become stuck.  Over time, the pressure builds up, until it becomes so great that the plates eventually jump past each other.  That’s an earthquake.

    If the plates just slid continuously past each other, we wouldn’t have this type of earthquake.  There would be no pressure to release.

    When the environment that we operate in changes, we have two choices.  We can adjust on a more or less continuous basis (innovation!) – this increases variance in returns, but it also reduces friction between our business model and the environment it operates within.  Since people don’t like this increase in variance, we often try to suppress it.  If we do this, the changes slowly build up pressure on our business model, until the pressure (and the business model) bursts.

    Experimenting to Increase Variance

    This is exactly the issue that Nassim Nicholas Taleb addresses in Antifragile.  He says:

    We can simplify the relationships between fragility, errors, and antifragility as follows. When you are fragile, you depend on things following the exact planned course, with as little deviation as possible—for deviations are more harmful than helpful. This is why the fragile needs to be very predictive in its approach, and, conversely, predictive systems cause fragility. When you want deviations, and you don’t care about the possible dispersion of outcomes that the future can bring, since most will be helpful, you are antifragile. Further, the random element in trial and error is not quite random, if it is carried out rationally, using error as a source of information. If every trial provides you with information about what does not work, you start zooming in on a solution—so every attempt becomes more valuable, more like an expense than an error. And of course you make discoveries along the way.

    In order to avoid being blown up by innovation tectonics, we need to experiment.  That is the point of the Innovation Loop:

    The Innovation Loop

    This is an approach that can help your organisation learn to love variance – and that is a healthier approach over the long-term.

    The next time someone tells you that their organisation is risk-averse, stop to consider whether or not it is really variance that they are trying to avoid.  If it is, Shane Parrish outlines five steps from Taleb that can help you learn to love variance instead.

    You should check them out, and use the Innovation Loop to help you build your experimental approach to business and innovation.  That will make it less likely that your business model will blow up.

    (diagram from Wikimedia Commons under a Creative Commons License)


    Enhanced by Zemanta