What’s the best way to respond to covid-19? There’s still so much uncertainty, it’s almost impossible to know. There are people and institutions that urgently need help – and first priority has to go them.
But there’s also value in taking a longer-term view in times of turbulence – I gave a talk last week on this topic, and you can see it here:
I won’t recap the whole thing, as it’s all there on the video. But here are some of the key points.
In the first half, I talk about some personal strategies we can use to think about things. One of the key concepts here is an idea that I raised in my last post: pace layers.
This is a great talk where Stewart Brand explains the origin and meaning of the pace layer idea, and then Paul Saffo expands on it.
There are two books that have helped me think about how to best take the longer-term perspective. One is How To Do Nothing by Jenny Odell. She looks at how to connect back to your local region as a method for combating the attention economy. The book came out of this post, which is also excellent.
The other set of ideas comes from Tyson Yunkaporta and his book Sand Talk. He talks about how the current world looks through an Australian Indigenous perspective. It’s a good way to start thinking about the 1000 year view of things.
One of the ways to think about this is to use the Cynefin Framework, developed by Dave Snowden. He also hosted a fantastic session on addressing covid-19 challenges using complexity-based approaches with a great panel that included Alicia Juarrero, Valdis Krebs, and Ann Pendleton-Jullian, moderated by Sonja Blignaut. All five of them are top tier thinkers, and it’s an interesting session.
We also included information about two sets of resources from the University of Queensland Business School. The first is a set of three of our classes on the edX platform at a greatly reduced rate – more information here. One of the three is the course that I put together on Design Thinking and Creativity for Innovation.
Even though there are no clear cut answers to questions about what we should do right now, I hope that all these resources can help us think a bit more effectively about how to best proceed.
And I hope that everyone that sees this is doing as well as you can under the current circumstances.
We just released a short course that I made for students at The University of Queensland. It’s called Ideas to Impact – and you can check it out here.
The goal is to encourage students to think more entrepreneurially. As part of it, I got to interview a lot of my favourite people at UQ, and for me, their stories are the highlights of the course.
Here is one of the short videos that I did for it:
Overall, there is about 60 minutes of videos, and you can take as long as you’d like working on the exercises.
So check it out, and please share it if you like it!
In part 1 of this post, Ralph revisited key innovation issues that were already addressed by us three years ago. In addition to these still highly topical issues, we’d like to raise another four points which we personally foresee key for innovation management in the time to come – making no claim to completeness:
Organizational Ambidexterity
As you can see from previous posts, I’ve been passionately advocating the importance of organizational ambidexterity for a couple of years now. From my own practice and observations as well as from recent discussions with other innovators in my local and global communites, it’s obvious to me that this issue is increasingly understood and becomes a major organizational requirement. It turns out more essential than ever for corporations to find ways how they can balance their innovation portfolio and to evaluate which structures, strategies and resources they have to put in place. Although, this is highly individual to each company, there may be some common cornerstones – such as the “Three Horizons” concept – structuring this way. Research confirms: development of exploration in parallel to exploitation capabilities proves to be mandatory for established companies in order to compete successfully and sustainably. Streamlining and simplifying existing businesses can be a major lever for resourcing important exploration initiatives. Note: Explorers outperform exploiters in the long run!
Tim’s Comment: I can’t tell you how often I come back to exploration/exploitation as a key concept. It doesn’t always translate to managers, however. Who wants to be an exploiter? One of the key issues in innovation management is figuring out how to frame these important ideas in ways that make sense to managers – finding the right story, metaphor or phrase.
Co-Innovation and startup engagement
One way for established organizations to strengthen exploration is by developing internal capabilities in order to overcome their inherent inertia. Another way is to “outsource” exploration through external engagement with startups. Thus, organizations acknowledge their inertia and focus on their exploitative strengths, rather than on their explorative weaknesses. Steve Blank and Evangelos Simoudis point out that todays’s R&D departments are not capable of accomplishing the exploration work anymore. On top of this, from an incumbents’ point of view, there are legitimate reasons for rejecting a new technology. If it underperforms, there is no business case for adopting it unless there is improvement. Moreover, if the innovation is truly different, then the incumbent would have to overhaul its systems and operations to adopt it. That means high integration costs – and another reason to be wary of new innovation. But incumbents would be willing to make changes if a new technology proves to be truly disruptive and the long-term benefits are worth it. Therefore, more and more companies turn to establishing innovation centers in order to take a “wait-and-see” approach, rather than to predict the future: they connect with startups and increase their stakes in those whose fresh ideas turn out to be taking off.
Most companies will continue to favor a “safer” approach in the time ahead, even while facing disruption. This suggests, this path to explorative innovation may be more appropriate for them. A key issue will remain how to establish co-innovation best and how to leverage new ventures in order to attain strategic or innovation goals. What’s more, proven benefits are also on the side of startups: corporate-backed startups tend to exhibit higher innovation rates compared to those backed by traditional, independent VCs.
Research confirms large companies as well as entrepreneurs to rate the importance of collaborative forms of innovation higher for the future. Further, the ROI (return on investment) of collaborative innovation was found to have been increasing recently. In light of rising connectedness, thinking in complementarities and co-creating in ecosystems with small and large partners (as discussed above) will increasingly take hold. One recent example for strategic complementarity is the announced partnership between GM and Lyft.
Tim’s Comment: There’s one other way that this idea plays out too – figuring out how to use lean startup techniques inside of established organisations. That’s been the core issue in the work that I’ve been doing with the CSIRO. The Stanford Social Innovation Review also looked at how to do this inside of not-for-profits. The advantage to using lean startup is that it increases your exploration ability, as Ralph says, and it also increases your capability in experimenting, as discussed in Part 1.
Digital Transformation
Digital Transformation – the use of digital technology to radically improve performance or reach of companies – affects every industry sooner or later. It will become a hotbed for innovation in 2016 and the coming years. On the one hand, it requires tailored digital strategies for companies, entailing technology-enabled, but highly customer-centered innovation. On the other hand, digitalization poses challenging requirements on organizations to become capable of going about these innovations, becoming truly user-centered and picking up the needed speed for the digital age. Although it should be obvious to companies that they jeopardize their existence if they don’t pursue digitalization with the required focus and speed, there seems to be a severe deviation between target and actual. BCG comments:
(…) it appears that even within the technology sector, many companies are not getting the message; on average, only about a third of executives project big data and mobile will have a significant impact on innovation in their industries over the next three to five years. Even fewer are actually investing in them. (…)
Consumers, who have been educated by the likes of Apple, Amazon, and Google in the possibilities of digital technologies, have moved quickly up the adoption curve. Digital technologies make their lives easier and better, and they want more digital – and mobile – interaction from the companies and other organizations that they do business with. (…) Companies are proving slower to adopt digital. (…)
As of the first quarter of 2014, 30 percent of Fortune 500 companies did not have a mobile app, and less than half had a mobile website. Most companies are not targeting mobile products and capabilities in their innovation efforts. The B2B marketplace has also been slow to catch on. Digital and mobile are only gradually making their presence felt there. (…)
We would expect to see the most intensive innovation focus in big data, given all the attention that has been devoted to the ability of digital data and advanced analytics to generate new products, markets, and revenue streams. Indeed, BCG research shows that big data leaders generate 12 percent higher revenues than those who do not experiment with big data. They are also twice as likely as their peers (81 percent compared with 41 percent) to credit big data with making them more innovative. (…) Still, three-quarters of our respondents said that their companies are not targeting big data in their innovation programs.
These results seem to complement findings of a recent study, conducted by MIT SMR and Deloitte. One major finding was, that organizations can be categorized in different digital maturity and awareness levels. Depending on the maturity level, distinct objectives and priorities are reported (see figure below). “Early”, digitally immature organizations (mostly without any digital strategy) focus on cautious, operationally-driven point investments for improving customer experience and engagement, as well as for increasing efficiency first. They aim at capitalizing on digitalization to advance their existing businesses. Mature organizations (following a dedicated digital strategy), in contrast, also rate bolder objectives, such as improving innovation and transforming the business, as prioritized objectives. From this, it becomes obvious that a certain organizational readiness seems mandatory in order to make use of digital technologies for innovation, let alone transforming business models.
What are critial conditions and factors contributing to digital innovation success in sufficiently mature companies? I’d like to highlight a couple of important ones – it’s where research intersects with my personal experience:
Digital strategy: Developing and pursuing a digital strategy drives digital maturity. Without a coherent set of vision, priorities and objectives, an organization will hardly be aware and prepared to tap into the transformative power of new technologies.
Dedicated labs or teams: Companies with dedicated cross-company labs or innovation teams are more than twice as likely to have launched at least one major digital innovation within the last 3 years.
C-Suite mandate and sponsorship: Of those with labs or teams with direct C-level sponsorship, 100% have shipped significant digital products, indicating a strong C-level buy-in does help get more major initiatives out the door.
Two-speed organization: A two-speed IT operating model decouples the digital business and traditional business with its legacy systems in order to cope with distinct pace and innovation speeds for each of both. This can be considered a special case of organizational ambidexterity in the digital transformation context. Setting up an independent digital organization is a good way to get things moving quickly, but only if the digital organization collaborates closely with the rest of the business and is properly aligned with the back-end IT developers.
Tim’s Comment: This is a huge gap for most firms right now, at least in Australia. It’s critically important because most of our forecasting tools are based on the assumption that the future will look roughly like the present. That’s been a reasonably safe assumption to make for a long time, but that’s no longer true.
Accelerated shift towards customer experience innovation
The coming years, probably decades, will be determined by two major shifts. First: Services already account for over 60% of the GDP of 35 of the top 40 economies in the world. Business activities, both B2B and B2C, tend to continuously shift towards differentiating services as digital technologies enable new business models (such as sharing services or product-as-a-service, cue: circular economy) as well as make products comparable and accessible on a global scale – and therefore more and more a commodity. Second: Accelerating deployment of novel digital technologies become the norm on the side of companies, but even faster on the side of customers. 75% of all digital data is now created by consumers, much of it via handheld devices. The increasing use of mobile devices results in “always on”, more demanding and powerful customers. Further, ongoing digitization is increasing the number and variety of customer touchpoints. That makes clear: we have been entering a new age of customers and services.
This combination of shifts implies some mandatory changes for companies. They have to
make their business customer-centered, rather than product-centered
serve customer needs in the context of life events, rather than selling products
shift from customizing products to individualized experiences
optimize the customer journey across all physical and digital touchpoints
Which impact does all this have on innovation considerations? To me, it definitely indicates innovation management will have to focus strongly on the customer experience (CX) by adjusting or renewing business models and adressing one-to-one engagement. Well-suited approaches, such a experience design or jobs-to-be-done help innovation initiatives putting the customer in the center. However, most companies are not yet adept in innovating truly customer-centered and need to build these capabilities in order to stay competitive. Forrester argues:
In the Age of the Customer, consumers are in control of their interactions with businesses. Inundated by endless sources of information, customers expect ready access to content that is personally relevant in the context of what they are doing and accessible anytime, anywhere, and in the format and on the device of their choosing. Attracting, winning, and retaining customers in this environment requires a concerted effort from across the business: The organizational structure, company culture, and business technology must all be aligned in service of the customers, in the spirit of delivering them exactly what they want. For this reason, digital and customer experience strategies are inexorably linked. Most every change that organizations make to aid in their digital transformation is also in pursuit of a better customer experience, whether directly or indirectly.
Gartner predicts that by 2018, more than 50 percent of organizations will implement significant business model changes in their efforts to improve customer experience. Research further confirms CX innovators to outperform their peers. The number one lesson to be learned for the digital era: companies that “own” the end customers, serve their contextual needs and provide a superior customer experience by means of appropriate – mostly platform-based – buiness models are going to win the customer’s trust and take the lead!
Which key innovation issues should companies and innovators have on their agenda in order to stay ahead in 2016 and beyond? Some advisory points in a nutshell:
Rather than using broad-brush approaches, align your innovation activities with integrative concepts that allow to differentiate but complement distinct innovation contexts. Once again: one size never fits all!
Develop business model innovation capabilities and provide for essential preconditions – first and foremost: CEO sponsorship and autonomous organizational space.
We are moving towards a co-creative platform economy. Therefore, evaluate whether to orchestrate your own platform or just participate in an other’s. Either way: be part or be out!
Develop a culture of experimentation for exploring new businesses, but also for strengthening existing businesses. You will get one of the most critical success factors for innovation in reward: speed.
Make sure your organization operates ambidextrously. Invest sufficient resources in explorative innovation because explorers outperform exploiters in the long run.
Innovation is not accomplished solely by one company any more. Reach out to the right partners for co-innovation. Engage particularly with startups if you prefer to play it “safe” but yet intend to drive radical or disruptive initiatives.
Prior to tapping into the huge innovation potential of digital transformation, build your company’s strategic readiness by conceiving the digital “big picture”. How to go about digital innovation? Setting up a dedicated digital unit, mandated and sponsored by the C-suite might be a promising start.
A new age of customers and services is on the rise. Shift your thinking and offers from customized products to individualized and contextualized services. Customer experience innovation will be the emerging battleground!
What are your key innovation issues for the time to come? We look forward to hearing them in the comments.
“One of my pedagogy professors said an interesting thing once: teachers spend their time in the classroom teaching, while students, who you’d hope would spend the time learning, are actually studenting; that is, performing the gestures they’ve been taught to perform to seem like legitimate students.”
-Christy Wampole, The Other Serious, p. 231
This quote from Christy Wampole is interesting. It lets teachers off the hook a bit – I know a few that simply perform the gestures of teaching. But this idea of “performing the gestures they’ve taught to perform” is useful.
We certainly see this in innovation – maybe there is something like “innovationing: performing the gestures that we’ve been taught to perform to seem like legitimate innovators.”
In other words, Innovation Theatre.
Here is what it looks like in entrepreneurship:
Going to meetups, being in groups, doing startup weekends, etc. but never actually building anything.
Talking about your idea all the time. But not building it.
Forcing everyone to sign an NDA before you’ll tell them about your idea, because you don’t want the idea stolen.
Even if you build something, you never put it in front of people or ask for their business, because it’s not ready yet.
You focus completely on your idea, not on the problem you’re trying to solve.
You tell everyone what you’re disrupting
And here are the symptoms of Innovation Theatre inside an organisation:
You talk a lot about what Google Apple would do. Or Uber.
You buy innovation management software, and expect it to create innovation.
You do something that generates a bunch of ideas, without any time or resources allocated to executing them and making them real.
You’re willing to consider all new ideas, as long as they don’t cannibalise your existing business.
You treat innovation something you bolt-on to business-as-usual, instead of treating it as core business.
Innovation Theatre is bad because when it is performed, the actors can feel as though they are innovating, and making progress, when in fact they’re simply wasting their time.
Innovation Theatre is a particular danger in a time of great hype. Some may feel a need to get some of that innovation stuff, so they end up performing Innovation Theatre instead of genuinely changing how they act.
There are three flawed ideas people hold that create Innovation Theatre.
Flawed Idea #1: Ideas are the most important part of innovation. This is the most common innovation mistake I run into, and you can see this throughout many of the examples. The way to change this idea is to act. First, start executing ideas rather than just thinking about them. You need to build an innovation process. Second, build a bias towards action, not thinking. As Jerry Sternin says:
It’s easier to act your way into a new way of thinking, than think your way into a new way of acting.
Flawed Idea #2: I know what customers need. None of these Innovation Theatre actions involve building a deep understanding of what customers actually need. The underlying assumption is that we already know. This is rarely true. The way to change this idea is to engage deeply with the problem you’re trying to solve, rather than getting hung up on your idea, or your features. When I started out in sales, we were taught to sell benefits, not features. The only way to know what a benefit is is to know what problems your customers are trying to solve. Methods that can help with this include design thinking, ethnography, and customer development.
Flawed Idea #3: Becoming more innovative doesn’t require any real change in the way we act. Innovation always requires a change in behaviour – and it requires it of both the creators and the users of the new idea. The way to change this idea is to turn innovation into a habit. Innovating requires resources – time, money, and attention. The principles behind it are simple, but implementing them is not easy. Consequently, you don’t get innovation instantly, you build an innovation capability over time.
Innovation is executing new ideas to create value. The remedies to all three flawed ideas behind Innovation Theatre are embedded in that definition.
Let’s stop performing the gestures we’re taught to perform that make us seem innovative. Instead, let’s act. Innovation, not Innovation Theatre!
I recently had a chance to catch up with my friend Ben for a quick coffee while I was traveling through Seattle. As usual, our discussion was great, covering all kinds of ideas. At one point, he said something I loved:
Mountain bikers always say ‘if you look at rocks, you hit rocks.’
It’s a simple idea, but it strikes me as profound. The follow up to that is that if you see space, you hit space.
One of their findings jumped out at me – a question they asked is “what are your barriers to business success?” Here are the answers for three groups of firms: those that don’t innovate on the left, those that do some innovation in the middle, and the novel innovators – the ones that come up with completely new to the industry innovations – on the right.
For the non-innovators, everything gets in the way. All they see are rocks, so they hit rocks.
But for the general innovators, the main barriers are learning challenges and contracting constraints. The big finding is that for the novel innovators, there are no external barriers. They don’t see rocks – they see space.
As Rita Gunther McGrath said last year at the Drucker Forum – all of our innovation barriers are self-inflicted. We can choose to focus on rocks or space. As John, Jerad and Martie-Louise show, what we focus on has a lot to do with how we perform.
If you think about that, you can see that time is important – you can’t do all three things instantaneously.
Here are two important ideas:
Within an organisation, innovation is the process of idea management.
New ideas diffuse along an s-curve.
If we put these two ideas together, we can see how time works in innovation.
Here are the parts of the idea management process:
If we order the steps as:
Idea generation
Idea selection
Idea execution
Sustaining ideas
Diffusion
Them we can map them onto the S-Curve like this:
Here is what is going on:
Idea generation: there is no idea to diffuse if we don’t have them in the first place. However, the best processes have constant feedback built in to them, so that ideas improve as we go along. This is an essential part of the lean startup approach (which we can use in established organisations as well).
Idea selection: there are two ways to approach this. First, we can select ideas before we start working on them, so they happen at the start of the process as shown. Second, we can use a more experimental approach, where we choose ideas as we test them out. This means that there is idea selection taking place during the invention phase too.
Idea execution: we have to make the idea real – there is no innovation without this.
Sustaining: this part is tricky for larger organisations. Sustaining involves keeping people involved and excited as we go through the periods marked Y and X in the diagram. The value for X is always larger than we expect, and it is easy for people to lose enthusiasm for an idea as we go through the start of the diffusion process. This can kill innovation.
Idea diffusion: like selection, there are two approaches to this. First, we can wait to work on getting our new idea to spread until after all of the development work is done. This makes diffusion much harder. It is better to use the second approach, which is to be thinking about idea diffusion all the way through the process.
There are several important points to come out of thinking about innovation in this way:
The best innovation processes have all five parts interacting. This follows from the discussion of both idea selection and diffusion. It is more effective to think of this as a continuously interactive process, rather than a linear one. To that end, instead of thinking about the process as I’ve put it in the first diagram, you can just as easily picture it this way:
All of our process diagrams [in major corporations] are linear, boxed diagrams that go one way. But entrepreneurship is fundamentally iterative. So our diagrams need to be in circles. We have to be willing to be wrong and to fail.
The second point is that the timing of our new innovations is important. Timothy Lee wrote a great piece on Vox on the timing of newspaper innovations called Newspapers weren’t too late to online news – they were way too early. He makes two important points. The first is that it takes a long time for us to figure out what new technologies are for (the value of X in the diagram above is much longer than we expect!):
30 years is a typical period of time between the first experiments with a new technology and mainstream commercial success.
The first mouse was invented in 1965, but it took until the mid-1990s for mice to be a standard computer feature. The first packet-switched network was invented in 1969, but the internet didn’t become mainstream until the late 1990s. Multitouch interfaces were first developed in the early 1980s, but didn’t become a mainstream technology until the iPhone in 2007.
That suggests we shouldn’t underestimate the disruptive potential of technologies, like self-driving cars, personalized DNA testing, and Bitcoin, that seem exotic and impractical today.
The second point is that experiments in the flat part of the S-Curve typically fail. Lee outlines many of the ideas that newspapers tested in the 1980s and 1990s designed to bring news online – they all failed. The result:
Indeed, part of the reason that newspapers were slow to adapt to the web is that by the time the web got big in the 1990s, newspapers had been experimenting with online services for two decades. And based on those experiments, they concluded that online services weren’t a serious threat to their business.
This reflects two common innovation problems. The first is that we often expect new ideas to be adopted instantly. This, of course, is never true. That is why it is so important to understand the S-curve.
The second problem is that we often expect new technologies to simply fit into existing business models. This is what happened to newspapers. However, one of the reasons that the S-curve starts out flat is that new technologies require new business models. Business model innovation is the learning tool that helps us discover the value in new technologies.
Innovation takes time. When we don’t understand the importance of time to innovation, we substantially decrease our chances of success. We end up looking for quick wins, with a guaranteed return on investment, rather than patiently building the systems that will enable us to succeed over the long term.
To innovate successfully, we must understand the role of time.
If you’re a startup attacking a large, established competitor, you don’t have too many advantages. The incumbent already has a lot of existing customers – that’s why they’re large. They have clear channels to market, established supply chains, revenue, money in the bank. They have everything. How can they lose?
If you attack them head-on, you don’t just need to be better, you need to be 10X better. That’s a big jump.
What should you do?
Your one big advantage is that your business model is not locked-in, but your opponent’s probably is.
Here are two examples. First, the New York Times. Stowe Boyd points to a great quote about them from an interview with Felix Salmon and Jonah Perretti:
I was a little bit surprised that the report didn’t spend much time tackling the hardest issue, which is why do they need to have so much revenue? It’s because their cost structure is made for print. When you look at how much revenue comes from print and the scale of their operation because of print, the challenge that they’re facing moving forward is how do they move into a post-print world….
It just seems like if you’re reading a secret internal report for The New York Times, the things that people would be stressed about, isn’t that, oh, the website’s not good enough, or they haven’t moved fast enough with this feature or that feature, but more like how do we deal with this very different cost structure of our future business, compared to our past business.
When digital-only competitors like Huffington Post, Politico, and the myriad blogs and news sites that have arisen over the past few years started out, they didn’t try to compete with the Times head-to-head. That is a losing proposition. Instead, they innovated the business model. This is nearly impossible for the large incumbent to copy, because they can’t easily change their cost and revenue structures.
The second example is Barnes & Noble. In the 80s and 90s, B&N and Borders became enormously successful because they became enormous. Instead of carrying 10-20,000 titles like most bookstores did at the time, they created a competitive advantage by carrying 120,000 titles.
That worked fine, until Amazon. When Amazon started to carry all the books, then 120K wasn’t much of an advantage. On top of that, B&N and Borders were competing with a firm that had a much lower cost structure, since Amazon didn’t have to invest in all the prime real estate that you need to carry a lot of physical books. The size, which had been their key point of difference, was now a big disadvantage.
If you’re starting out, you don’t just need a great idea. You need an innovative business model too – this is the best weapon you have against large incumbents. The one big advantage that you have is that you’re not locked into whatever business model is currently the dominant one. Here is how Benson Garner puts it:
Contrary to popular belief it’s not finding a great idea that is the most challenging part in a corporate or start-up venture. One of the most difficult tasks is the search for the right business model to support your idea. It’s hard work and the threat of failure lurks around every corner.
As we face competitive turbulence, the key question to ask is: if we were starting our business right now do, would we do this? If you were starting a newspaper right now, would you invest 90% of your assets and resources in print? If you were starting a bookstore, would you make it massive and undifferentiated, in a retail location with high rents?
No.
That’s the attacker’s advantage – every time the answer is no, they don’t have to do it the old way. They can innovate the business model.
The Problem with Solved Problems that Aren’t Solved
Phil was certain that his company had their innovation problems solved. After all, they had a dedicated innovation team, they had idea management software, and they had started a big internal PR effort to highlight successful innovations.
What could possibly go wrong?
Lots, actually. Over the past few years, I’ve met plenty of people in Phil’s position. They think that they have made the investments that are required to make their organisations more innovative. So they end up feeling perplexed when they find, after a few years, that their organisations are no better at innovating then they were before they made those investments.
They thought that innovation was a solved problem, when, in fact it was not. Usually, this is a sign that we haven’t solved the right problem.
One of the big issues here is that there are actually five roles that an innovation team can fulfil. We need to have all five filled if we are going to innovate successfully, but many innovation efforts only cover a couple of them. We need to better understand these roles.
Five Roles for Your Innovation Team
Innovation is the process of idea management. To get the most out of your innovation team, you need to align its responsibilities with the parts of the process that need the most help. The process looks like this:
With this in mind, here are the five roles that your innovation team can fill:
Information Facilitation: when you do information facilitation, you find information about innovation, and distribute this to people that are generating ideas. This will help them figure out how to best execute the new ideas. In this role you can also work on developing processes and infrastructure that support all parts of the innovation process. This type of group is most active in supporting idea generation.
Opportunity Consultant: a group doing this will do everything that an Information Facilitation team does, but they will take a more active role in selecting ideas. They work to ensure that the ideas that are pursued connect with the organisation’s overall strategy. In this role you work on developing the best possible set of criteria for evaluating ideas, particularly for fit with objectives.
Opportunity Enabler: this type of group goes one step further – they work to connect ideas with those that have the resources to execute them. Enabling collaboration is a big part of this role – you need a group in this role if you are pursuing an open innovation strategy. This type of team will also work on developing implementation plans, and trying to quantify outcomes and learnings from new initiatives. Opportunity enablers are active in supporting all steps in the innovation process – idea generation, selection, testing and diffusion.
Idea Execution: this is the most active role you can have – this is a group that doesn’t just support the innovation process, they actually undertake all the steps. Most R&D groups fall into this category. Usually, with this type of group, there is no problem with getting innovative results – the bigger challenge is integrating their ideas back into the core business.
Business Model Development: genuinely new innovations usually need new business models to help them realise their full market potential. Unlike the other four roles, this one can be mixed with the other four.
Which Type of Team is Best For You?
Let’s go back to Phil – how does this help with his problem? The issue in his firm is that the top managers set up an innovation team that has the skill-set and resources available to be Information Enablers, but the managers are expecting them to an Idea Execution team.
This, obviously, is a big problem.
And it’s not uncommon. Nearly everyone that sets up these teams thinks that they are building an Idea Execution team. You can’t set up an innovation group, with responsibility for innovating, without also provided the resources that are required to do this. If you have limited resources (or limited commitment), it is better to acknowledge up front that your new team will be Opportunity Consultants or Enablers. Or even Information Facilitators. The more clear you are about the group’s objectives, the more likely it is that they will be successful. And the objectives have to align with the resources.
It’s worth noting that the same problem happens with innovation software. Organisations often buy a piece of idea management software and then assume that they have innovation handled. This is not true – you still need all of these roles filled.
Closely related to this, as you move up the scale, the resources and skills that you need increase. Don’t expect one group to fill more than one or at most two of these roles. To some extent the lower-level activities are included as you move up the ladder, but not entirely. If you need to have all four roles filled within your organisation, you probably need to have more than one group working to support innovation. Or you at least need to have responsibility for these different roles clearly assigned to different people within one large team.
The last tricky bit is figuring out where business model innovation fits. Many organisations think that it should come after all of the other stuff has happened, as in the picture above. Here’s the issue: even if you sink a bunch of resources into building an Idea Execution team, you still might not get better at innovation. That’s because they still only do two parts of innovation – they execute new ideas. But innovation is executing new ideas to create value.
If you’re just executing new ideas without creating value, you often end up frustrated. That’s why business model innovation is so important – it is a great tool for discovering the value that your new idea actually creates.
What you really need is an innovation system that looks like this:
If your innovation team does anything more complex than information sharing, you should probably think about building business model innovation capability into the group as well. It is not something that comes in at the end of idea generation, selection, and execution. It needs to happen in conjunction with all of these steps.
This is the best way to ensure that your organisation will be skilled at all of the parts of the innovation process.
To build an innovative organisation, you need to have all five of these roles filled. If you form an innovation team, they will often fill some, but not all, of these roles. If you buy a piece of innovation software, you face the same issue.
If you don’t understand what the different roles are, and how you’re addressing them, then it’s likely that you will be in the same situation as Phil – investing many resources into innovation, without seeing much return.
That’s one of the core ideas from Joseph Schumpeter, and it’s one of the reasons that the group for people studying evolutionary economics is called the International Schumpeter Society. I’m at the 15th ISS Conference right now in Jena, Germany, where I got to hear Stan Metcalfe, one of my favourite evolutionary economists, speak today.
Stan is just a wonderful speaker, and his talk today was filled with gems. Even though he was presenting a paper that was very theoretical, there were a lot of lessons in the talk for all of us. The quotes from Stan are in bold, followed by my comments:
Innovation is action which, ex ante, could be considered a ridiculous error in judgement. This is a critical point – the whole issue with innovation is that we can’t know in advance if it’s going to work or not. If we know it will work, it’s not innovation, it’s just a financial decision. Many of the struggles that people have with innovation comes from this – we want certainty. But if we’re going to innovate, we must actively seek out uncertainty.
This creates tension for many of us.
Innovation is the bridge between scientific knowledge and economic action. Stan frames the core question in economics as: how do develop wealth from knowledge? This question drives the growth of firms, and the development of economies. One of the themes that has consistently come up in the conference so far is the difference between invention and innovation – it’s innovation that bridges knowledges and economics.
Quoting Schumpeter: No one can give an account of the principles by which innovation is done. This is a tough one for those of us that try to teach innovation. I think that this quote is almost certainly true. The implication of this is that to manage innovation, we need to be trying out lots of ideas, and live with having a fair number of them not work out.
Stan had another quote from Schumpeter:
Most innovative ideas come to nothing, of those that do not, 90% still fail.
Picking out my cat Schumpeter from the veterinarian
We think of the economy as knowledge-based, but it’s really ignorance-based – otherwise we couldn’t innovate. This is an idea from the often overlooked economist George Shackle. Shackle’s entire research program was based around the question: how can we act when we don’t know what will happen?
You make a profit by having different expectations from everyone else. If innovation is a leap into uncertainty, it means that people will have different expectations of how new ideas will work out. Some will be excited by them, others will think that that they are ridiculous errors in judgement. It’s only when we try them out that find out who was right. But no matter what, there’s no money in a consensus.
Stan also talked a lot about how he’s not interested in averages, he’s interested in outliers. When we’re studying innovation and business, that’s absolutely correct.
However, if we look at the average evolutionary economist, we find someone that is interesting and generous – Stan is an outlier on both dimensions, but the average is still pretty good. That’s why I like hanging out with them for a few days whenever I get the chance.
One of the critical parts of innovation is getting your great new idea to spread. How you tell the story around the idea has a lot to do with how successful we are in doing this.
I’ve been thinking a lot about this because of two recent events: giving a talk at TEDxUQ and the wrap-up of our projects this year in our collaboration with Wharton in their Global Consulting Practicum (GCP).
First, here is the TEDxUQ talk (please share this if you like it!):
The main point of the talk is that to innovate, we need three things: a new idea, made real, that creates value for people. It is the third part that enables the idea to spread. If you’re missing one of the three parts, then you have a trigger for innovation: fear, fantasy or frustration.
This is where the GCP projects come in. In this program, we have a team of ten MBA students – five from UQ and five from Wharton. They work together on a live consulting project for clients that want to expand their business in North America (and if you’re an Australian firm that wants to work with us on this, there’s more information here). Since we started on this in 2011, I have put together all of the academic content on the UQ side, and acted as a mentor/guide for all of the teams. It’s a lot of work, but incredibly rewarding.
We’ve run seven projects now. Each project runs for six months, and it ends with the team giving the client a final presentation summarising their recommendations. It’s a great learning experience, and the commercial outcomes are usually pretty good too. Wharton has been running this program for 35 years in several countries, and they say that our project with Lorna Jane is one of the most successful that they’ve ever had.
Simplistic: this is what we get when we dumb things down too much, or don’t understand the topic very well. In the GCP projects, this is most common in the first couple of months. Simplistic ideas are dangerous because they falsely make it seem like there are simple solutions to complex problems.
Complex: complex presentations are ones that reflect a huge amount of the detail surrounding a problem – often too much detail. The business problems that we are often trying to solve are indeed complex. Complex solutions accurately reflect this reality. However, the avalanche of detail often obscures the real issues at hand, making it difficult to see a path forward.
Simple: this is what you get when you have a deep understanding of the situation. I used to have a manager that said if you couldn’t explain a complex idea to people in simple language, then you didn’t understand it yourself. Simple communication embeds a great deal of complexity in (relatively) easy-to-understand language – and usually this is what we should be aiming for.
By the end of the GCP projects, the teams always have a mountain of a data and a deep understanding of the issues facing the clients. The problem is: how can we communicate the recommended course of action as simply as possible? The teams often struggle with this. They end up presenting a very complex set of ideas, because they fail to find the simple story that lies underneath these ideas.
My biggest role in these projects is to help them do this.
Doing the TEDx talk gave me more insight into this.
Bratton’s argument is basically that we have two choices: simplistic or complex. His accusation is that because TED talks reduce complexity, then they must be simplistic.
So I understand why someone could worry about TED’s goal of delivering something valuable in videos of less than 18 minutes. If TED talks were the only way that ideas could be shared, they might have a point. But there are countless communication forms out there in the world. Before you can answer the question “Are TED talks dumbing people down?” you really need to ponder: “compared to what?” The critics pushing the oversimplification argument seem to believe that if only people weren’t wasting their time on silly TED talks, they’d be reading books, taking evening classes, poring over scientific papers, or at the very least subscribing to the critic’s uniquely brilliant blog.
…
We certainly don’t think any TED talk offers all there is to know on any topic. Of course not. But you can learn enough to get excited about knowing more. A TED talk is not a book. It is not a peer-reviewed scientific paper. It can’t be either of those things. Nor does it want to replace them. On the contrary, it wants to amplify them and bring news of their significance to a broader audience.
What I discovered is that this is pretty hard. My talk went through many iterations. I was particularly concerned about dealing with the issues around Australian aboriginal art simplistically – there are many complex social issues here that go well beyond the issues of art.
As I got feedback from a lot of great people my ideas got closer and closer to simple – thanks Nancy Pachana, Nilofer Merchant, Martie-Louise Verreynne, Rick DeWitt, Louis Ialenti and Allyson Rosen for the help! I ended up cutting a lot, and re-arranging ideas until I got to the final version.
Start by asking the questions that I posed in a previousposting regarding your personal narrative:
Given the choices I’ve made and the actions I’ve taken throughout my life, what’s the personal narrative that has led me down this path?
Is this personal narrative one that can help me to achieve the things that I really want to achieve or is it inhibiting me in some significant ways?
How could others help me to achieve even more impact and what’s in it for them?
What specific choices can I make and what actions can I take in the next day, week and month that will start to evolve my narrative in ways that will help me to achieve more of my true potential?
Finding the narrative is part of the challenge of simplicity. It is what the GCP teams often struggle with, and it was a struggle for me too.
But if we want to change the world, we have to communicate our complex ideas simply. Not simplistically, but simply.
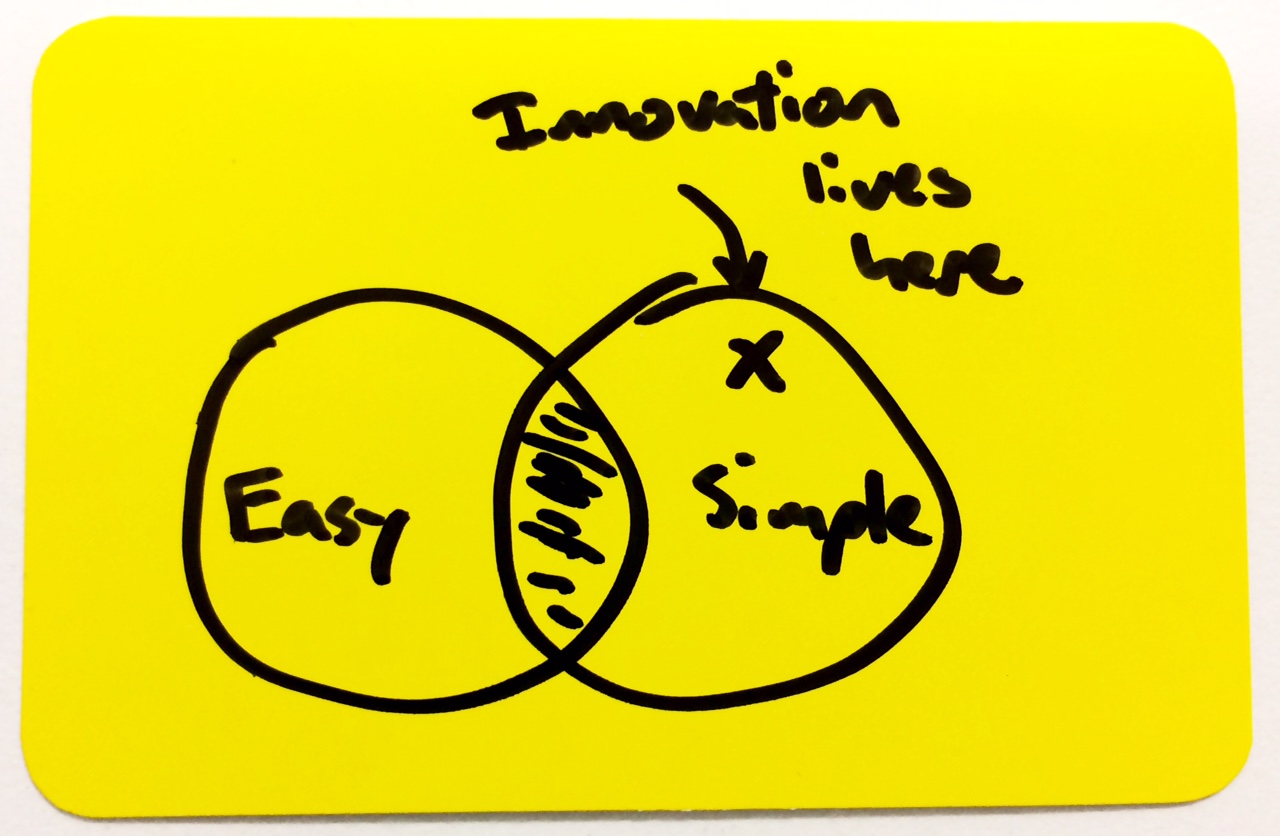
Communicating simply is another of those things that is simple, but not easy – just as most important things are.
3M is one of the most innovative companies in the world. Each year, their target is to have more than 30% of their revenue come from products that are less than four years old. To do this, they must constantly come up with new stuff.
To find this new stuff, they spend about 6.6% of their annual revenue on Research & Development. The average large US corporation spends less than 2% of revenues on R&D, so 6.6% is a whole lot.
But think about this for a second – what is 3m spending the other %93.4 of their money on?
The rest of the money goes to executing ideas that they’ve already had.
One of the challenges of innovation management is finding the right balance between the old and the new.
Finding the balance between the old (the 93.4%) and the new (the 6.6%) is tricky. You need the core business to work smoothly and efficiently in order to realise the value of your great new ideas. But this requires different skills and metrics than we need to use to come up with those great new ideas in the first place.
There is a lot of hype in the business press about the dangers of clinging to the past, and much of it is justified. But all the excitement about building better products and companies can make us forget that most new ideas are bad and most old ideas are good. After all, that is what Darwin predicts. The death rate of new products and companies is dramatically higher than old ones. Dozens of new breakfast cereals fail every year, while Cheerios and Wheaties persist.
…
My aim is not to convince you to discard every routine your company uses and to devote all efforts to inventing new ways of thinking and acting. On the contrary, doing routine work with proven methods is the right thing to do most of the time.
…
Does this mean that you should stop trying to innovate? Not at all. The problem is that the world does change, new technologies are developed, competitors come up with superior products and services, and consumer preferences change. These are the times and place when innovation is crucial. … Many companies have made a lot of money by creating new and better future. So, although it usually entails a high failure rate and a lot of resources, every company – or at least part of it – needs to keep trying to discard old ways and replace them with new and better ways.
This is a challenge. If we devote ourselves only to the new, then we will fail to take advantage of the great ideas that we generate. But if we only concentrate on optimising for the present, then we’ll get killed by the future. And the pace of that problem has increased significantly since Sutton wrote the book in 2002.
… our job as innovative business leaders is to manage the present while inventing the future. We must recognize that we are always a product of what we’ve done and who we aspire to be. It is not enough to lead our current businesses; we must also lead our future businesses. … To grow new markets means making yourself uncomfortable.
The part about feeling uncomfortable is also what Sutton is getting at – that is why the ideas in his book seem weird. He recommends 11.5 ideas that you need to execute in at least part of your business in order to create the future:
His ideas are:
Here is the list (note I say 11.5, but there are really 12)
1. Hire slow learners (of the organizational code).
1 ½. Hire people who make you feel uncomfortable, even those you dislike.
2. Hire people you (probably) don’t need.
3. Use job interviews to get new ideas, not to screen candidates.
4. Encourage people to ignore and defy superiors and peers.
5. Find some happy people, and get them to fight.
6. Reward success and failure, punish inaction.
7. Decide to do something that will probably fail, then convince yourself and everyone else that success is certain.
8. Think of some ridiculous or impractical things to do, and then plan to do them.
9. Avoid, distract, and bore customers, critics, and anyone who just wants to talk about money.
10. Don’t try to learn anything from people who seem to have solve the problem you face.
11. Forget the past, especially your company’s successes.
Finally, as a summary, if you look at these, a reasonable conclusion is that, although creative places can be a lot of fun at times and being happy is linked to creativity (sort of, I’ll explain in a later post), note also that Creative companies and teams are inefficient (and often annoying) places to work.
This is hard. If you look at Sutton’s ideas, you can see that implementing them will create tensions within an organisation. It’s much easier to focus only optimising the present, or on building something completely new. But those two extremes lead to failure.
As Paul Hobcraft correctly pointed out to me once in an email – “if innovation were easy, everyone would be doing it.”
Yep. One of the challenges is finding the right innovation balance. 3M has done it, and so have others. If we can too, then our odds of success go up.
How can we make our organisations more innovative?
That’s a big question. My colleagues John Steen, Jerad Ford and Martie-Louise Verreynne, working with Ernst & Young, just released a report that gives us some insight into the answer.
The consistent finding is that productivity is driven by three things: innovation, competitive capabilities, and collaboration.
This might seem counterintuitive. This is a highly competitive industry – it’s dog eat dog. And it’s all about efficiency, right? Who can spare resources to innovate?
Well, it seems like the only firms that can spare resources to innovate are the ones that want to succeed.
It’s a story that holds true beyond oil & gas.
One of the questions that they asked is “what are your barriers to business success?” Here are the answers for three groups of firms: those that don’t innovate on the left, the middle is firms that do some innovation, and the right are the novel innovators – the ones that come up with completely new to the industry innovations.
For the non-innovators, everything gets in the way. But for the general innovators, the main barriers are learning challenges and contracting constraints. The big finding is that for the novel innovators, there are no external barriers.
Here’s what they say in the report:
The most remarkable feature is that innovators do not cite external factors when asked about barriers to their business success. Innovators are impacted by such factors (e.g. red tape), but not to the extent that the factors are seen as impediments to business success. The finding suggests that the effect of the ‘barrier’ is more dependent on the organisation than the barrier itself.
A Japanese proverb springs to mind: “Fix the problem, not the blame.”
Novel innovators are those firms who have implemented solutions that are wholly new to the industry. When they were asked about barriers to their success, constraints were rarely mentioned at all. This surprising finding deserves closer scrutiny. We do expect novel innovators to find creative solutions to particular problems. What is unexpected is that often, those solutions that novel innovators come up with somehow resolve all problems. This does not suggest that novel innovators operate in a different world, but rather, they operate on a higher plane. That is, where others see only barriers, innovators see opportunities. Red tape, green tape, problems in execution and the list goes on… these become ‘catalysts’ for innovation and perhaps even ‘pathways to productivity’. For novel innovators, this list of commonly cited issues is not perceived as barriers to productivity. Industry, take note.
This is a really important finding. When I talk with firms that struggle with innovation, all I hear about are the barriers. There are labour problems, and too much competition. Their industries are over-regulated, and they face too much uncertainty.
The big idea in this work is that novel innovators face these problems as well, but instead of letting them prevent innovation, they use them to spur innovation.
What she finds is that stress causes reduced health outcomes – but only if you believe that stress is bad for you. If you believe that stress is simply a biological sign that there are things happening that you must respond to, then your health outcomes are identical to people that aren’t operating with significant amounts of stress.
In other words, the different health outcomes depend on whether or not we view stress as an obstacle, or a trigger.
This is basically the same as the findings from John, Jerad, Martic-Louise and E&Y. If you view issues like red tape, labour problems and competition as barriers, then they will make you less competitive. But if you view them as innovation triggers, you will be much more likely to succeed.
Innovative firms in this study are nine times more likely to find ways to increase productivity than non-innovative firms are. A big part of the reason why is that the innovators respond to barriers differently. Instead of seeing them as something that blocks progress, they view barriers as a trigger that requires an innovative response.
Constraints spur innovation, if you have the right attitude. Where others see only barriers, innovators see opportunities.
If this is true in the ultra-competitive oil & gas industry, it is probably true in ours as well.