Tag: joseph schumpeter

  • Innovation: Action That Could Be Considered a Ridiculous Error in Judgement

    Innovation drives economic evolution and growth.

    That’s one of the core ideas from Joseph Schumpeter, and it’s one of the reasons that the group for people studying evolutionary economics is called the International Schumpeter Society.  I’m at the 15th ISS Conference right now in Jena, Germany, where I got to hear Stan Metcalfe, one of my favourite evolutionary economists, speak today.

    Stan Metcalfe

    Stan is just a wonderful speaker, and his talk today was filled with gems.  Even though he was presenting a paper that was very theoretical, there were a lot of lessons in the talk for all of us. The quotes from Stan are in bold, followed by my comments:

    Innovation is action which, ex ante, could be considered a ridiculous error in judgement.  This is a critical point – the whole issue with innovation is that we can’t know in advance if it’s going to work or not.  If we know it will work, it’s not innovation, it’s just a financial decision.  Many of the struggles that people have with innovation comes from this – we want certainty. But if we’re going to innovate, we must actively seek out uncertainty.

    This creates tension for many of us.

    Innovation is the bridge between scientific knowledge and economic action.  Stan frames the core question in economics as: how do develop wealth from knowledge?  This question drives the growth of firms, and the development of economies.  One of the themes that has consistently come up in the conference so far is the difference between invention and innovation – it’s innovation that bridges knowledges and economics.

    Quoting Schumpeter: No one can give an account of the principles by which innovation is done.  This is a tough one for those of us that try to teach innovation.  I think that this quote is almost certainly true. The implication of this is that to manage innovation, we need to be trying out lots of ideas, and live with having a fair number of them not work out.

    Stan had another quote from Schumpeter:

    Most innovative ideas come to nothing, of those that do not, 90% still fail.


    Picking out my cat Schumpeter from the veterinarian
    Picking out my cat Schumpeter from the veterinarian

    We think of the economy as knowledge-based, but it’s really ignorance-based – otherwise we couldn’t innovate. This is an idea from the often overlooked economist George Shackle.  Shackle’s entire research program was based around the question: how can we act when we don’t know what will happen?

    You make a profit by having different expectations from everyone else. If innovation is a leap into uncertainty, it means that people will have different expectations of how new ideas will work out. Some will be excited by them, others will think that that they are ridiculous errors in judgement.  It’s only when we try them out that find out who was right.  But no matter what, there’s no money in a consensus.

    Stan also talked a lot about how he’s not interested in averages, he’s interested in outliers.  When we’re studying innovation and business, that’s absolutely correct.

    However, if we look at the average evolutionary economist, we find someone that is interesting and generous – Stan is an outlier on both dimensions, but the average is still pretty good.  That’s why I like hanging out with them for a few days whenever I get the chance.

  • Are Creativity, Entrepreneurship & Innovation the Same Thing?

    Are Creativity, Entrepreneurship & Innovation the Same Thing?

     Who Owns Idea Execution?

    Scott Belsky tries to unravel the mechanics of creativity in his book Making Ideas Happen.  He includes this equation:

    belskyquote

    Making Ideas Happen = (The Idea) + Organization and Exuction + Forces of Community + Leadership Capability.

    He goes on to say “Ideas are worthless if you can’t make them happen.”

    Now consider this from Daniel Isenberg in Worthless, Impossible and Stupid: How Contrarian Entrepreneurs Create and Capture Extraordinary Value:

    Most of us would agree that innovation has something to do with the tangible manifestation of novel ideas.  But entrepreneurship is about the creation of tangible value.  Ideas help, but the sine qua nons for entrepreneurs – hard work, ambition, resourcefulness, unconventional thinking, salesmanship, and leadership – will usually trump brilliant ideas.

    When he says “innovation” he clearly doesn’t mean the same thing that I mean when I say it:

    Innovation is executing new ideas to create value.

    Here is one way to picture it:

    Thinking of it visually emphasises that all three parts of the definition.  Everyone gets the “new idea” part of it.  But it’s not enough to have a great idea, you also have to execute it.  And even after you’ve done that, you’re not finished.  It’s not innovation if you’re not creating value for people.

    So the people talking about creativity, entrepreneurship and innovation all make a distinction between having ideas, and creating value with those ideas.  And none of us want anything to do with just the “having ideas” part of the whole thing.

    Does that mean that we’re talking about the same thing?

    Innovation, Entrepreneurs and Entrepreneurship

    Strangely, this confusion didn’t exist 100 years ago.  When Joseph Schumpeter wrote about innovation, he was talking about the process of creating value from ideas.  My definition of innovation basically builds on his.  The “entrepreneur” was the person that innovated.  And “entrepreneurship” didn’t exist.

    Check out these stats from Google NGram tracking the use of the three words in books published between 1900 and 2000:

    Screen Shot 2013-08-07 at 6.36.16 PM

    Innovation is the most commonly used of the three words, and “entrepreneurship” as a concept was basically born in the 1950s.  Why?  Because the nature of innovation changed.

    When Schumpeter was writing, innovation basically happened in startups.  So entrepreneurs were people that created innovation by starting new firms.  But the first half of the 20th century saw the rise of corporate innovation – which meant that we had to be able to distinguish between innovation taking place in large organisations and in startups.

    That’s when we started to distinguish between innovation (which usually meant ideas executed in established firms), and entrepreneurship (ideas executed in new firms).

    So Where to Next?

    To answer my earlier question, I don’t think that we’re quite talking about the same thing when we talk about creativity, entrepreneurship and innovation.

    In his forthcoming book The Myths of Creativity, David Burkus says:

    Although there is still no precise and agreed-on definition of creativity despite nearly one hundred years of research on the subject, there appears to be at least a small consensus.  Creativity is seen by most experts in the field as the process of developing ideas that are both novel and useful.

    Again, there is an emphasis on use (value!) – but the main concern is the processes through which we generate and execute these ideas.

    This is obviously an issue of great importance in innovation, because better ideas lead to better outcomes.  Provided, of course, that we execute them!

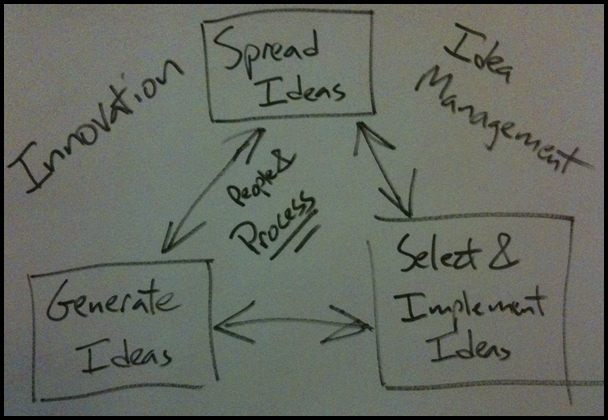
    Innovation, then, is this process of idea management.  Entrepreneurs are still the people that innovate, and entrepreneurship is doing this through the vehicle of a new venture.

    If we accept all of this, there are a few important implications:

    • Everyone focuses on idea execution for a reason. Why do all three fields want to own idea execution?  Because trying to improve your performance by simply generating more ideas is one of the biggest mistakes that both people and organisations regularly make.  All of us focus on execution because this is where the gap is.  The great news here is that it means you don’t have to be a genius to be a creative entrepreneur.  You can do this by being really good at executing.
    • We need to put entrepreneurs back into innovation.  It’s too easy to forget that innovation is driven by people.  We need to put more focus on entrepreneurs – the people that are creating value out of ideas – and less on tools.  It’s people that create value.  If we’re in a big organisation, we need to figure out how to liberate and support our entrepreneurs.  If we’re in a startup, we need to figure out how to build a business model that creates value out of our great ideas.  Both approaches are people-based.
    • We need to be clear on our definitions.  Creativity, entrepreneurs and innovation are all important, and they all intersect.  People that study or practice any of these fields should be working together, rather than creating artificial distinctions between them.  My definitions might not be the best, but I do think that they have some historical weight to them, as well as reflecting fairly common usage.  But I’m definitely willing to have a discussion about what’s what!

    This important because while the three areas have slightly different meanings, they share the same goal – to create value for people.  This is what leads to longer lifespans, higher standards of living, and more interesting and fulfilling work.

    Enhanced by Zemanta
  • Innovation Challenge: Your Market is Never Stable

    Innovation Challenge: Your Market is Never Stable

    Earlier this year I ran across a couple of striking charts from Horace Dediu’s fantastic Asymco blog.  He regularly puts together very compelling stats on the state of the technology industry, and this post looked at the market share for various operating systems over time.

    The first chart shows the the market share of various systems, and you can see the rise and then slip of Microsoft here:


    operating systems


    You can see how Texas Instruments dominated things around 1977, only to be replaced by first Atari, then Commodore, before it disappeared entirely.  Atari and Commodore held on until the early 90s, then they disappeared as well.

    The tipping point from the Apple OS to Windows happened early too, followed by a long period of domination for Microsoft right up until about 2007.  Currently Android + iOS have about 55% of the personal computing OS market, and Windows has about 45%.

    However, if you look at the data another way, looking at the total number of OS sales, you can see a slightly different story.  Here’s  Dediu’s original chart:operating systems 2


    This chart shows a slightly different story.  The market share for Windows isn’t falling because its sales are dropping – it is falling because with the advent of smartphones and tablets, the overall size of the personal computing market has doubled.

    There are several important innovation lessons here:

    • When a market is forming, the race is for the best business model.  If you look at the market shares around 1982, Atari, Commodore, Apple and Microsoft all had significant market shares.  Microsoft won because it developed a robust business model the fastest.  As Greg Satell points out, they won because they developed modular architecture first.  Furthermore, while their code wasn’t open, their API was – and openness is a big innovation advantage as well.
    • In a mature market, the threats come from outside.  Microsoft still dominates the desktop.  The problem right now is that the desktop is being rapidly overtaken by more portable computers.  Even as Apple revived a bit on the desktop with the introduction of the iMacs in the early 2000s, their market share in this market still didn’t go up that much.  It only took off with the iPhone and then the iPad.  The threats to Microsoft’s position came from segments outside of their core market.  They knew this was coming for a while, but it wasn’t until the introduction of Windows 8 that they really attacked this issue head-on.
    • Your market is never stable.  One dangerous assumption that organisations make is that they know what market they are in, and that this will remain stable.  Information technology is wreaking havoc on traditional industry boundaries.  John and I visited a research lab for an engineering company last week, and it was very clear from the projects that they are working on that the firms that will win in this traditionally very conservative industry will be the first ones to become fully knowledge-based.  As projects get more complex and more expensive, managing the flow of data becomes increasingly important.
    • Nothing ever stays the same.  The Justice Department didn’t need to break up Microsoft.  The evolution of the market has taken care of their dominant position.  It’s always tempting to think that today’s winners will also be front-runners tomorrow.  This is very rarely true.  That’s why we have to innovate.

    Richard N. Foster has looked at this problem in a couple of outstanding books.  He outlines the key issue in this interview:

    Let me tell you how I got to the term “creative destruction.” In the 80’s, I was in a search for “the excellent company” – the all-seeing, all-knowing, all-wise company that made all the right moves in advance, and that made more money for its shareholders than any of its competitors. This was the permanent outperformer stock – the really good deal. I looked at 4,000 companies over 40 years, and what I found stunned me. There was no such company, and there never had been such a company!

    I thought something had to be wrong. Was I looking at the problem in the right way? No company had been able to outperform the market for any substantial length of time. (GE came as close as any, but didn’t do any better than the overall index). Somehow the market – managed by nobody – was performing better than all the brains on the planet. But why? Then I realized that the reason markets outperform companies was closely tied to what Joseph Schumpeter called “creative destruction.” This was actually a phrase that came from the Hindu religion, dealing with the transformation of an individual throughout their life, from creation, onto death, and ultimately rebirth.

    My friend Geoff sent me this quote from Joseph Campbell last week:

    The interior of man has been essentially the same for 40,000 years, since the first emergence of Homo Sapiens Sapiens. Myth has to do with the spiritual potentialities of this constant, this human being. But the images of myth must be derived from the environment of today and in this place. There is therefore a constant transformation of the image, but not of the reference.

    This is probably true – it explains why so many of the stories that we respond to as humans have such similar structures, and similar points.

    But another constant is that in business, things change.  If you’re running a business, that’s a very good argument for innovating.  As innovators, our job is to invent the future.


    Enhanced by Zemanta
  • There Must Be Forty Ways to Innovate

    There Must Be Forty Ways to Innovate

    Innovation is the Process of Idea Management

    I am always suspicious of one-size-fits-all solutions. They are very easy to sell in a book or a blog post, but they rarely work in the real world. There’s too much variation.  That’s a big part of why best practices are stupid.

    Just think about the innovation process.  I picture it like this:

    How many different ways can we do those three steps? I didn’t give this list a huge amount of thought, so I’m sure that I’ve missed a few, but here are forty ways to innovate:

    Idea Generation

    • get to the edge
    • scratch your own itch
    • be a genius
    • blue sky r&d
    • applied r&d
    • ask your customers
    • watch your customers
    • ask your people
    • brainstorm
    • gamestorm
    • think outside the box
    • think inside the box
    • co-create
    • scenario planning

    Selection and Implementation

    • experiment!!
    • r&D
    • stage/gate
    • innovation team
    • innovation coach
    • expert panel
    • minimum viable product
    • iteration
    • gut instinct
    • does it fit with what we’ve always done?
    • do whatever the CEO wants
    • focus groups
    • market testing
    • A/B testing
    • team consensus

    Spreading Ideas

    • network
    • traditional distribution
    • viral marketing
    • advertising
    • influentials
    • small seeds
    • word of mouth
    • lead users
    • co-creation
    • pull strategies
    • partnerships

    What Combination Should We Choose?

    These forty innovation methods can be combined in more than 2300 different ways.  So why would should we think that only one way would work?

    Within industries we often see one model used.  In pharmaceuticals, ideas are generated through applied R&D, they are selected and developed through a stage/gate process, and new innovations are diffused through traditional channels.  If everyone is doing it this way, you’d be crazy to stray too far from the pack, right?  It would be nuts to come up with new ideas through a co-creation process with your customers, right?

    Well, maybe not.

    Joseph Schumpeter said:

    (Economic) development in our sense is then defined by the carrying out of new combinations.

    Carrying out new combinations.  If there are at least 2300 ways to combine the different parts of the innovation process, why not innovate how you innovate?  That’s what Procter & Gamble did when they developed their open innovation initiative Connect & Develop.

    Schumpeter also said that innovation isn’t just about coming up with new stuff.  He said it more elegantly than that, but that is the point that he was making.  Our processes – the way we do things around here – are things that we often take completely for granted.  If you figure out a way to innovate your process, it could lead to a completely new business model.  And that’s one of the best forms of innovation around.

    It’s time to start thinking about innovating how we innovate.